(406) 206-7571
We are used to hearing plenty of chatter surrounding interest rates: Will they be raised? Be lowered? But behind those interest rate decisions is another integral part of monetary policy: bank reserves.
Bank reserves are funds that big commercial banks hold in accounts at the Federal Reserve. They are a key tool in influencing interest rates. Banks use these reserves to settle payments with one another and manage day-to-day cash needs. Think of it simply as the bank account for your bank.
Most of us don’t care to think about how many reserves a bank holds at the Federal Reserve. But we do care about what happens to interest rates and inflation.
How much cash is available in this system matters because reserves help the Fed maintain control over short-term interest rates. And these short-term interest rates eventually influence the borrowing costs that consumers and businesses see by impacting rates on credit cards, business loans, lines of credit, and other borrowing costs.
To understand how cash reserves influence interest rates, it is helpful to look at three different reserve environments: abundant, ample, and scarce.
An abundant reserves environment is exactly what it sounds like: banks collectively have substantially more reserves than they need to comfortably operate.
Imagine a bank already has far more available cash than it needs. Receiving another dollar is not going to meaningfully change much. Likewise, losing a relatively small amount probably will not cause much concern. This is what makes reserves abundant.
Following the Fed’s large asset purchases during the pandemic (a tactic to keep the economy afloat amid the shutdowns), trillions of dollars of reserves entered the banking system. With such a large cushion of liquidity, banks had little need to compete with one another for additional reserves.
This is where the connection to interest rates comes in.
When reserves are abundant, adding or removing small amounts of reserves has almost no effect on the rate banks charge each other for overnight loans, also known as the Fed Funds Rate. There is already so much cash available that banks do not need to offer significantly higher rates to get more of it. This keeps that fed funds rate stable and close to the rate the Federal Reserve would like to see. But it is important to remember that when there is more money to go around, there is more room for prices to rise.
Over the past several years, the Fed has reduced the enormous amount of excess liquidity created during the pandemic, an attempt to cool inflation. As reserves declined, the banking system moved from an abundant reserves framework to an ample reserves framework.
Ample reserves represent the middle ground. Banks still have enough cash to comfortably meet their needs, but they are no longer sitting on the enormous cushion that existed when reserves were abundant.
Another thing to note is that ample is not a specific dollar amount, think of it as more of a range.
When reserves are ample, there is still plenty of cash available, but every dollar begins to matter a little bit more. Small changes in the number of reserves may cause some movement in short-term rates, but not enough to interfere with the Fed’s control over interest rates.
This is essentially the Fed’s desired middle ground. Enough liquidity to keep the financial system functioning smoothly and short-term interest rates under control, without maintaining much more reserves than the banks need that could ultimately cause other problems.
If reserves were to fall below the ample range, the banking system would eventually become scarce.
The word “scarce” may sound alarming, but it doesn’t necessarily mean banks have run out of money. In fact, the United States operated with a scarce reserves framework before the 2008 financial crisis and it was not what led to the crisis.
Scarce simply means banks hold much smaller reserves relative to their liquidity needs.
With less cash sitting readily available at the Fed, banks must manage their reserves more carefully. A bank that needs additional reserves may need to borrow them from another institution.
And when more banks are competing for a smaller pool of available reserves, the price of borrowing that money, the interest rate, becomes much more sensitive to supply and demand.
Think of it this way: when reserves are abundant, another dollar barely matters.
When reserves are ample, another dollar matters somewhat, but banks still have plenty of available cash at their disposal.
When reserves are scarce, every dollar matters much more.
This is why relatively small changes in reserve supply can produce much larger movements in short-term interest rates when reserves are scarce.
The Fed has spent the past few years reducing the size of its balance sheet and removing some of the excess liquidity that entered the financial system during and after the pandemic.
By late 2025, the Fed determined that reserves had moved from abundant into ample range and stopped shrinking its balance sheet. Today, the Fed’s stated goal is to maintain ample reserves, not intentionally push them into scarcity or bring them back up to abundance.
The aim is to not drain as much cash from the banking system as possible. Instead, the Fed is trying to find the appropriate balance.
The Federal Reserve sets a target range for the federal funds rate. One of the Fed’s main tools for keeping that rate where it wants is the interest rate it pays banks on their reserve balances, also known as the interest rate on reserve balances or IORB.
When reserves are ample, the Fed can change the rate it pays on reserves and influence other short-term rates without having to constantly add or remove cash from the banking system.
But if reserves became too scarce, supply and demand would begin playing a much larger role. Banks needing cash could bid interest rates higher, making it more difficult for the Fed to keep rates where they want. This is why the amount of reserves matters; they help create the environment in which the Fed’s interest rate policy can do what it’s supposed to.
Abundant reserves can put upward pressure on inflation since there is more money available in the financial system. More money moving through the economy can lead to higher spending and higher prices. Over the past several years, we have seen very high reserve levels alongside higher inflation, increased government spending, and growing debt. While abundant reserves are not the sole cause of all these problems, it is a good reminder that more is not always better. We are encouraged to see the Fed moving away from the extremely high reserve levels of recent years towards a more balanced approach.
Summary: In this video, Christa Hudak, CFP®, ChFC®, CKA®, Cofounder and President of CoCreate Financial, explores an important but often overlooked part of financial health: knowing where your money is actually going. She outlines out a simple exercise to track your expenses for a small period of time so that you can see clearly where you are spending, identify any areas where spending may be out of alignment with your priorities and make any changes that you would like. Remember, it is okay to use your resources! You want to ensure you are spending on the things that truly matter to you.
2025.09.24 Podcast Episode 7
FULL TRANSCRIPT
Christa Hudak: Do you know how much money you spend? Most people don’t. But it’s an important number to be aware of. Before we get too far let’s talk about why this is important from a financial planning perspective.
The first reason is that good retirement planning requires that we understand how much money you’re spending in the present because we’re going to base what we want your retirement expense to be like on that number.
Everybody’s lifestyle is a little bit different and even if you’re planning to make some adjustments in retirement either up or down it’s going to be about adding or subtracting from this number. And basing it on what your current situation is.
The second is that a lot of people want to make adjustments before they hit retirement. Maybe you’re thinking about changing jobs to get something that is going to have a different outlook for your earning or starting a business or something along those lines. Being able to pull this number will give us an understanding of what’s feasible for you and what the adjustments you’re going to have to make are going to look like.
And then finally if you’re overspending, this is a critical issue and awareness of your spending is the first step in fixing it.
So this might sound simplistic, but I’m going to walk through each piece and cover multiple situations in exploring this concept of how much money do I spend and look at it from a couple different angles.
The first thing is just in a very broad overview to ask, “What’s happening to my balances over time?” So, this is just looking at a snapshot. Where does everything sit now, and where did it sit maybe six months ago, and a year ago? So, do you have any growing consumer debt? If that’s the case that’s a critical overspending problem that you’re going to want to address. Or, maybe you don’t have any debt growing but you don’t have any savings accumulating either. Everything that comes in goes out and all the balances are staying flat. This is a very normal situation because it’s almost like magic that if we don’t have a plan when more money comes in it just goes out.
And then finally if you truly are spending like than you’re earning you’re going to see a pile of money accumulating somewhere. So, if you are not spending everything you are making or overspending, there should be evidence of that someplace in the form of a growing account balance.
So now that we have an idea of your general situation let’s work on identifying how much you’re really spending. Now, you could start with tracking all of your expenses for a couple months and looking at that but the problem with that is most people are not consistently good at tracking their expenses and it’s also going to delay our ability to provide any analysis or look at what’s going on. So, that’s not a strategy that I would start with and it’s going to delay our ability to jump into some meaningful planning.
The other misstep I see is that if I were to hand you a budget worksheet for you to fill out what would you do? You’re going to put down the information you know, you know you’ll pull some number, and you’ll write down accurately things like your mortgage, your car payments, your insurance bills, and maybe even your utilities. But then you’re going to get to some categories like clothing, and eating out, and travel, and your grocery bill and you’re probably just going to start throwing down some numbers that you say, oh its probably about this.
Well, the reality is that’s not going to be an accurate number to work with, and it’s not going to be a good foundation for being really realistic of what’s going on in your situation.
So here’s what I want you to do instead. Get a worksheet or an excel file if you like those kinds of things, and then I want you to pull at least three months of all your bank statements and credit card statements. But you could go for a longer time period, all the way up to 12 months if you want a really good, consistent picture.
And then I want you to go through and categorize every transaction. Now you can decide how specific you want to be in your transaction categories. You can get really granular if you want, but you can also give yourself broad categories too. That’s going to make it a little bit easier to work through it. The more granular you are the more opportunity you have to evaluate your specific spending but it’s a lot more work in putting this all together.
So, you’re going to go through and categorize every transaction, and I do mean every transaction. You’re going to come across things that you’re like well that’s an abnormal expense. That’s not going to happen again. And, I want you to include it. You can feel free to make a note about it, but to remove it would really give us an inaccurate picture because unfortunately a lot of times we find that even though it may not be that specific expense, abnormal expenses are actually very normal in life.
Now, for my small business owners I do want to make a note. This process is going to be a little bit more complicated for you. Because it’s common for business owners, especially small business owners, to put some expenses that they would have to cover personally on their business, and this can have a wide range of the level that this takes place of, you know some business owners might put lots of things on their business that are really personal transactions, whereas other business owners might have a very distinct separation from their business. But there might be certain things that if you didn’t own your business you’d have to go pay for it personally. A great example would be paying for your cell phone on your business. So, your phone is a business expense, and you’re using it in your business, but if you exited your business, you would have to go get a phone and pay for it. If we’re doing retirement planning we need to know about all those expenses that are going to get added to the personal side. So be sure to take a look through your business books and identify any of these expenses we would need to shift to the personal side, if you exited your business.
So now that we’ve worked through categorizing your expenses through a period of time, you can average that out both in total, and in each category. And then we’re going to just ask some questions and do some evaluation. What do you notice about your spending habits? What surprises you? Are there categories that you feel like should be lower or higher? And how do you feel about how you are spending your money? Are there any changes that you would like to make?
Remember, reviewing your spending isn’t about trying to spend as little as possible. Instead, it’s about having good information in order to plan. And making sure that you’re funding the things that really matter to you. Setting yourself up for long-term success and awareness of your habits. It’s certainly an opportunity to re-orient if you don’t like what you see, or to start some conversations. But it’s not wrong to use your resources.
If you’d like help developing your plan and managing your investments we would love for you to reach out to us at CoCreate Financial. Thanks so much and have a great day.
Summary: In this video, Matt Hudak, AAMS®, CFP®, CEPA®, builds out a sample "Financial Architecture", which is a practical system for organizing your money so that it functions to support your goals. He explains it like a reverse budgeting approach that prioritizes directing income into the right financial "buckets," including cash reserves, debt repayment, retirement savings, flexible investment accounts, and charitable giving. By creating a clear structure for your cash flow, you can spend with confidence, reduce financial stress, and ensure your money is aligned with both your long-term goals and your everyday life.
2026.08.18 Podcast Episode 6
Matt Hudak: Hi, friends. I'm really excited today to talk to you about something that we do with most every one of our clients as they're getting going in their process. And then it really helps us to help them with their cash flow. It's a really effective way to think about budgeting. A lot of times when we're looking at how do you manage your expenses, how do you structure things, how do you set things up?
A problem that we run into is that most people aren't very effective at keeping track of their day to day expenses and keeping track of how to manage each category and all of the details of it. And Christa has done a phenomenal video talking about how you can do this well, how you can manage all of your expenses and understand what you're spending. (Watch that video here.)
But when we get to working with people day to day reality where we're not just simply trying to evaluate for a planning purpose what you're spending in a short term, managing it for the long term is a very difficult challenge for most people. So we've come up with through a lot of trial and error over the years, sort of a form of reverse budgeting.
And that's what we're going to talk about today. It's almost sort of similar to the pay it yourself first methods, if you've heard of that. But we like to call this establishing a financial architecture. And it looks at where you put your money, where you want it to go for the different goals that you have over the course of your lifetime, so that you can live the life that you want and be free to live that day to day.
When you have money in your bank account, it means that it's there for you to use because you've already put it where it needs to go and to the places that matter. And so everything left for you really functions well. So let's dive in. I'm going to get on my whiteboard. We'll spend a lot of time diagramming things out on camera here for you.
This is going to look very different in different contexts. So the example that we're going through, we'll try to make it universal and cover a lot of different pieces of it. Some may apply to you, some may not. As we're getting together and meeting, we're fleshing this out in real time together to collaborate and create something that works for your situation to expedite your actual cash flow management.
So let's dive in. First thing that we're going to do is we're going to create sort of a little timeline for our financial architecture here. And we're going to say this vertical dotted line is age 59.5. And there are a lot of different retirement ages. It’s really absurd. But I mean, Congress negotiates with itself to come up with all kinds of random ages, one of them being 59.5.
Some of you might have seen 66 in six months, or 65 and four months for your full retirement age for Social Security. You can't make this stuff up. But, well, somebody did in Congress. But there are a lot of different retirement ages, 65 is when you can take Medicare, but age 59.5 is for your retirement accounts. This is the age where you can draw without a 10% tax penalty on that withdrawal.
And there are some exceptions and there's some different tools and techniques to deal with that. But let's just say that at age 59.5, that's the age where you can access it, because barring some sort of extenuating circumstance, that's going to be your age. So we'll maybe do another video on that in the future on when you can draw and why and what are those exceptions to that age 59.5.
So you have your retirement accounts and we're going to work backwards here to the present. That's a terrible square. So I'm going to erase that and try again.
So you're going to have some retirement accounts. And if you come into our office and get to know us well, you'll learn that everything that I do, I can illustrate in a box. If you can't illustrate it in a square, it's not worth drawing. So you have your IRAs. We might also have 401k’s. You might have 403b's.
There are all kinds of different names for different retirement accounts that are in sort of this pretax category that we would say. So you put money in and then you don't pay tax on it when you put it in, or you get to deduct it on your taxes that year. And then when you withdraw the money, you pay taxes on it, and it grows tax deferred.
In these types of accounts, you also have Roth accounts which are very similar, but these are post-tax accounts. Your 401k’s often have a Roth option. You have a Roth IRA. And we'll do another video at some point to tell you which one makes sense for you. Basically, they're just flipped and turned over. So a Roth, you pay tax on the money now and then it grows without tax.
And then you don't have to pay tax on it when you pull it out. So it's tax free after that. Both of them makes sense in different circumstances. It's not that one is better than another they're just different. The Roth IRA, you can kind of have some circumstances where you can pull money out before your age, 59.5.
So that's kind of a neat tool when it works and makes sense for certain purposes. So these are the long-term funds. And as we're going we'll put some money in here. We'll show you how we get some money into these accounts for the long term. This we actually want to target in these retirement accounts how much you put in.
We don't want you over saving for retirement. And that's actually one of the biggest mistakes that we see people make when they're good savers. People who are struggling to save enough. We need to get lots of money into those retirement accounts for their security.
But when you have plenty and you have an abundance of resources, oftentimes we lock those up in things that are tax deferred for retirement. We get the tax benefits on them, but then we don't have them available for the things that we need in the interim. There are a lot of other goals that happen. Other than retirement, if you're familiar with our industry, you know that we sell products for three goals.
You know, death, retirement and college. And that's what we talk about in financial planning traditionally across the industry, because those are the things that the products are geared around. But you have a ton of life transitions that aren't involved in those in your financial plan needs to adapt and be flexible so that you can meet all of those different needs.
So we want to target enough in your retirement accounts that you have your basics covered, that you're stable, that you have that income set aside so that you're secure at that stage of life. But we don't want to over save there. So the other thing that we're going to do is we're going to jump over on our diagram to the other side of the spectrum.
You have your immediate needs because you've got to pay your bills and buy groceries and you need to eat and that matters. So you got your paychecks and those come in probably to your checking account most of the time. So you get you have a paycheck coming in. Maybe you have some emergency funds. Maybe you have a savings account.
And by the way, I'm not a huge fan of the term emergency fund. I think as a cash reserve is a better concept than an emergency fund because you don't want to put it in there and say, I cannot touch it ever, unless I'm on my deathbed and trying to figure a way out. Like it's really a reserve to smooth things out as time as you have, irregular expenses, things like that.
You don't want to touch it for random things, but if you need a new roof and you've got to make your deductible like you can, you can use it for that. It's not necessarily just for strict true emergencies. So I like the term cash reserves better than emergency fund for that reason. But your paycheck comes in and depending on where you're at and how you manage your resources, how practiced you are, how stable and comfortable you feel, this may or may not apply to you, but we really like to see people have a floor right in their checking account that's more than zero. You know, if you're having irregular expenses, you want to be able to have some slush fund in that checking account that you don't draw in there unless there's something irregular, so that you're not every single month pulling money in and out of that cash reserve fund. So we want to see maybe depends on who you are.
I'm going to use a round number and say $10,000 in here. And that may be for some of you that may be very far out of reach. For others of you, that might not be anywhere near enough, but we're going to pick some round numbers as we're going so that math is easy if we need it. So we might say $10,000 is the new floor.
So that's zero. And every time you go down, if you're spending one month and you hit $9,000 in your checking account, or $9,500 in your checking account, and we end up looking at that, you know, you've overspent that month more than what you earned. And that's one of the number one rules of finance is spending less than you earn and you'll be successful.
But when you're doing that, if you've spent more than you've earned, you just build that back up to $10,000 the next month or the next two months, or whatever that might be, rather than pulling from your emergency fund or even worse, having to put it on a credit card. Having enough cash is really, really important in your financial architecture and your overall stability, because if you don't, then you have to turn to sources that you don't want to go to for your basic needs, and it just builds up habits that are ineffective for your long-term wealth building.
So the next thing we're going to do on this diagram is we're going to add in some debt. And hopefully you don't have tons of debt. But debt is a tool. But it always mortgages the future. So we want to take it very seriously. When you have debt, we don't want to actively take out debt. That's not productive debt that's unsecured.
We don't want you to be overleveraged. If I use the term leverage, that means debt. Nobody that we encounter that has a significant amount of debt and leverage feels content in life and feels happy. Debt causes stress. It causes a lot of financial challenges. That doesn't mean it's always evil. It doesn't mean it's always bad. But we want to avoid it when we can and find other ways.
And when we do use it, we want to calculate it out and make sure that we're very, very strategic about it. But we want to make sure that we have a place on here to deal with any debt that you have. And then we're going to look at some other types of accounts on here, because, you know, you're going to put some of your paycheck because we're starting to build out a plan where we can put money where it needs to go.
So we're going to say, you know, your paycheck needs to start going into your checking account until you build up this floor. And then we're going to start to route money from your paycheck, maybe into this emergency fund. We'll set a goal, and we might split this out over time into some different, different percentages or different dollar amounts each month.
But we might set a goal in your emergency fund. And I'm going to say just to be random, $30,000. That's probably not a goal that we set, that we just try to tackle that straight away and get you to $30,000 before doing other things, because your financial goals are simultaneous, not sequential. And so we might say, once you get to a floor of 10,000 and $5,000, we'll just start to put a little bit of every paycheck into that emergency fund or that cash reserve fund.
But we're not going to go too crazy on that right away because there are other things to tackle. We're also going to put look at putting some money into your debt repayment. Might be mortgage, might be car payments, your credit cards. We figure out how to do that efficiently and how to maximize your ability to manage that debt well and to be effective in that. We want to pay that off.
Hopefully we want to pay that off eventually before you're retired, if you can. But it's also okay to have a mortgage in retirement. It's just a number that we have to figure out in different ways. But we want to be low debt, so we want to make sure we're figuring out how much can we put there. We'll talk more about how we come up with these numbers as we go.
Just bear with me here. So we're looking at that and then you've got your retirement savings. We want to decide how much do you actually need to save in retirement. So let's say your target is to have $1 million in retirement accounts.
We're going to look at that and say, well, in order to do that you have a certain amount that you need to save. Maybe that's $1,000 a month for that target. That might be a little bit more, might be a little bit less, could be a lot more depending on how close you are to that age. But let's say you want to get to $1 million.
So we're going to say let's shoot for that $1,000 a month. But maybe that's and that can come straight out of your paycheck and come out of your bank account happen automatically. It can happen at will. But, you know, people that do things automatically tend to be more effective and consistent. So when we're looking at that, it might be $1,000 a month, or you might be in a situation where you say, well, I don't have $1,000 a month of room, and the best that you can do is always the best that you can do.
So if you don't have $1,000 a month in your case, whatever that number might be, then we just say, well, where do we start? And we get something moving and we start building your habits of saving. And then we can adjust as time goes on. One of the biggest and most important things that we see people do is there's this big gap.
If you notice it, and I'm not, I'm just going to move my little tiny cursor here around. But this huge gap here where most of your life happens, if you can see that between here at your immediate needs, buying groceries and when you're able to start drawing on your earliest retirement assets, usually that's age 59.5. This is a massive time frame.
Depending on your age, this could be 30 some years for you. And what we want to do is we want to make sure that you have resources to buy homes, to pay for children's weddings, to save, for college, to move across the country to whatever it might be. There are so many different things to start a business.
There might to invest. Make a charitable contribution in your community to do something that you've dreamed about. This is massive and it's overlooked by most everyone that we encounter. Most people, even very, very successful individuals, don't realize that you can save in and invest in accounts like it was a retirement account without locking it up for retirement.
There are some different features of that we call these. You might see the technical term a brokerage account, but we just call these individual accounts, or joint accounts. So depending on whether you're married or how you have ownership of this. Ind.
And these function a lot like a bank account. They're not FDIC insured. They're SIPC insured there. You can invest in them instead of just having it invested in CDs or something like that, that the bank would go out and do or by making mortgages, making loans, which is what the bank is doing and paying interest. These accounts, you actually own things inside of them.
You can buy stocks and bonds and funds and all kinds of different things that are out there and different financial products in these accounts, and they're accessible instead of being taxed deferred, like your retirement accounts are these accounts, you can own things and you pay taxes on the profits of what you own in those accounts as you receive them.
Oftentimes, if you own things for a long period of time, a year or more, or if it's a you'll get long-term capital gains treatment, if it's a dividend you're looking at, if you had it for 60 days, you'll get the same long-term capital gains treatment on that, which is for most people in most situations, significantly tax advantaged.
In some cases, it's even taxed at a rate of 0%. So when we're looking at that, we want you saving here because you can put money, once you hit this $30,000, we might have you start to rout money here because you might want to buy a house. You might want to buy an investment property sometime, someday. And that might be something that you fund with money that's in this account.
It's hard to do that with the money in your IRAs and Roth IRAs. And you can. Yes, you can't own real estate in an IRA, but it's a very, very technical and often problematic process for people where you can get into a lot of trouble. So please call us if you're thinking about that or consult your tax professional on that.
And somebody that's an expert on the prohibited transaction rules with an IRA, so that you don't cause yourself a significant financial setback just by an accidental misstep. So we look at these brokerage accounts and you might have multiples. You might say, I want to save. Maybe you don't want to save for college, which is traditionally a 529 plan account.
A lot of people have heard that term. We can do those, but a lot of times people want to be engaged in saving for college outside of a college account because they might want to buy their help their kids by their first house instead, or start a business, or be more flexible with those funds than just setting aside for college.
So there might be one that we kind of informally title for kids. And these if you don't want to, if you don't want to use these for your kid right away because they're struggling in life or they have a challenge and you want to motivate them, you can hold that back. You can help, you can help them in different ways and be very flexible with that money.
And finally, you might see something on here that we might look at for our clients who give frequently. You might have what we call a donor advised fund, and there are other charitable vehicles. But we're going to keep it simple.
With these donor advised funds, you get to give to these like you give to a charity. You can invest these, but you can deploy out of them. You can use them to give them the funds to a charity anonymously. A lot of people like those features. But we might start to say, well, you know, you hit your target here, you have a home purchase goal.
So we're going to set some money that we're going to decide goes here. We're putting money everywhere it goes right out of your income stream, your cash flow stream. As soon as we can get that money out reasonably so that it's not sitting there because like me or anyone else, if the money's just sitting there, it gets spent.
It's just a law of human nature. And so with these donor advised funds, we can say, you know, give stock to them and accumulate some. Maybe you have a really high income here. Let's say you sold a property or a business or something like that that has a lot of taxes in one year. We can give a big chunk of that to a donor advised fund, or we can even give like fractional interests of those properties or businesses to the donor advised fund and save a ton in taxes that year.
And you can give that out over the next several years. So you can kind of pre give to the donor advised fund and then continue to give that to the organizations you care about at a pace that's appropriate for what you want to do for that organization. And you can get your kids involved in that. There's so many different ways that we can structure these on the savings side.
And then on the distribution side, you have a lot of different if you've done this right, you have a lot of different buckets that you can pull from. And you can be wildly tax efficient in retirement as well. When you're in that distribution phase and drawing on your assets for income. There are places on a financial architecture where we can put your real estate holdings, your business interests.
This just gives you kind of an idea of how we map it out. And what happens is at the end of the line, when we're all said and done, I'm going to make it pick a different color. Just for fun. Let's make it green for cash. Whatever's in here, when you've done this right and you've sent money right away, everything in here if I color this in, is all free for you to use.
It's available money. And what most people naturally do is they check their bank account. If there's an appropriate balance in there, they'll use it. And you're able to do that with this model, you're able to engage in a way that's just natural and how you're going to function just on a day to day basis, just as somebody who's just trying to spend less than they are and isn't super tuned into the details, but you're just going to be exceptionally functional for targeting each one of your goals over the course of your life.
So we're really excited to get to walk through this exercise with you. Building a financial architecture is actually really fun. I love doing it with clients and friends, and I just it's such a fun process to go through and iterate how you put your resources, where they reflect your values and your goals so that you can be effective.
The first half of the year has reminded us that the stock market rarely grows in a straight line. It has reacted to changing economic data, rumors about the future of interest rates, geopolitical events (war, changes in international trade policy/preference, etc.), Congress’s inability to function, and continued drama around investing in artificial intelligence. In the midst of the instability, we have seen strong returns in the first half of the year.
On one side, we’ve seen people recognize much of the instability that shows up in the headlines. When we speak with these people, we look at history, which reminds us that markets have consistently rewarded disciplined, strategic, long-term investors who don’t forget about the basic rules of investing. Time in the market matters, and not every business has the same risks. When you look at each business in your portfolio on its own merits, and take care to put them together so they complement each other, most of the headlines just become noise.
On the other side, we see many looking at the easy money promised by the AI investment craze. We would remind these people of the old adage “easy come, easy go”. We’ve long said that if it sounds too good to be true, it probably is. Investing indiscriminately in the stock markets at this stage certainly reflects these principles. Good investors aren’t like my dog, Stetson, when he sees a squirrel. They don’t let themselves be distracted by the newest, shiny thing. Instead, they repeatedly buy good businesses that provide consistent passive income.
Market fluctuations happen every year, and 2026 is no exception, but there are also many exciting opportunities on the horizon! In this month’s update, we’ll take a closer look at the current economic landscape, discuss key themes influencing markets today, and share our perspective on what they may mean for you moving forward.
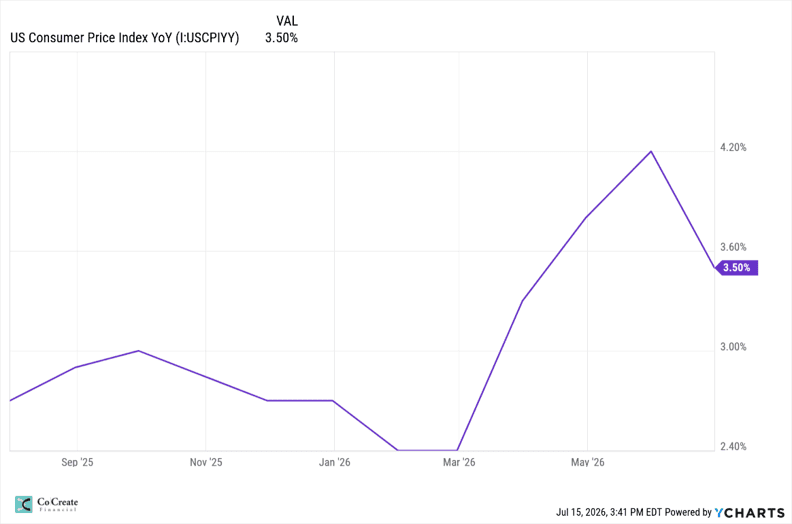
Few topics have received as much attention this year as inflation (again, nothing new), with changing feelings and predictions continuing to influence investors. CPI, or Consumer Price Index, is a measure of how much prices are changing for everyday goods and services over time. The U.S. Bureau of Labor Statistics released a report on July 14, 2026, that stated that CPI was 3.5% as of late June, meaning inflation has risen 3.5% year-over-year. When we look at the month-to-month numbers, inflation has decreased by 0.4%, largely due to the index for energy falling 5.7% in June after increasing consistently in March, April, and May. The question is whether that downward shift will continue into July as uncertainties surrounding the conflict in the Middle East continue to put pressure on energy prices.
While inflation has cooled considerably when we compare it to previous years, it remains high enough that the Federal Reserve, our nation’s central bank that is tasked with using different tools to keep our economy stable, is expected to take a cautious approach before lowering interest rates. For the everyday person, persistent inflation means everyday expenses like groceries continue to cost more than they did a year ago. For investors, inflation is one of the biggest drivers of interest rate decisions, making it an important indicator to watch. But the truth is, interest rates aren’t what drive markets, we can look at what people are investing in to see what the true drivers are.
In recent years, markets have scrutinized every Federal Reserve meeting and public comment closely, often reacting sharply to even small hints about future interest rate decisions. Since taking office, new Federal Reserve Chairman Kevin Warsh has signaled a different approach. Rather than providing detailed guidance about future policy, Warsh has emphasized that markets should focus on the underlying economic data instead of trying to anticipate the Fed’s next move. This is a step in the right direction and a huge positive for investors. Financial markets work best when they are free to move organically and are not being driven by constant speculation over recent headlines on each and every Federal Reserve speech or meeting.
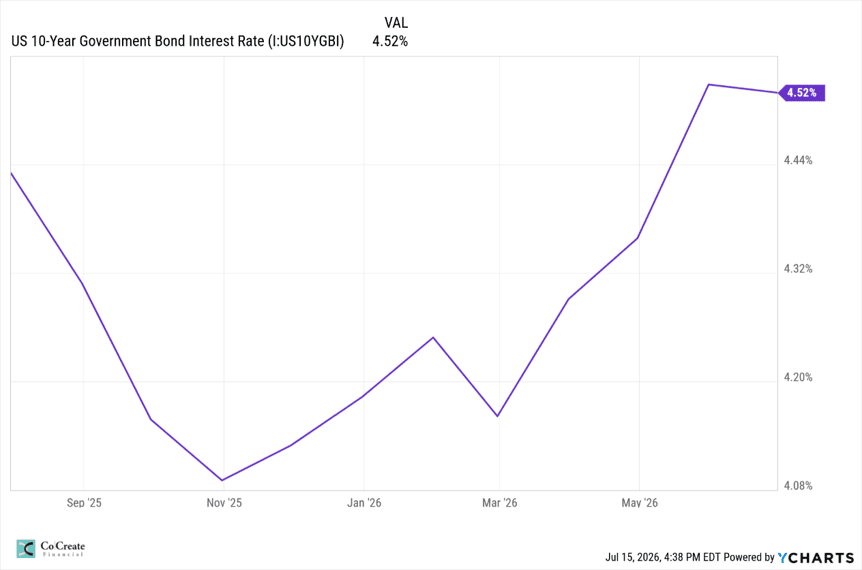
In that same vein, another important indicator to watch is the 10-year U.S. Treasury yield. Closely tied to inflation, the 10-year U.S. Treasury yield is the interest rate investors receive for lending money to the U.S. government for ten years. This rate has a heavy influence on mortgage rates and long-term borrowing rates. But it is important to note that the 10-year U.S. Treasury yield is different than the Fed Funds rate, which has more of an influence on short-term borrowing. Over the past few months, the 10-year Treasury yield has climbed to approximately 4.5%, reflecting expectations that interest rates may remain elevated while inflation continues to moderate. Higher yields generally increase borrowing costs for consumers and businesses, which can slow economic activity.
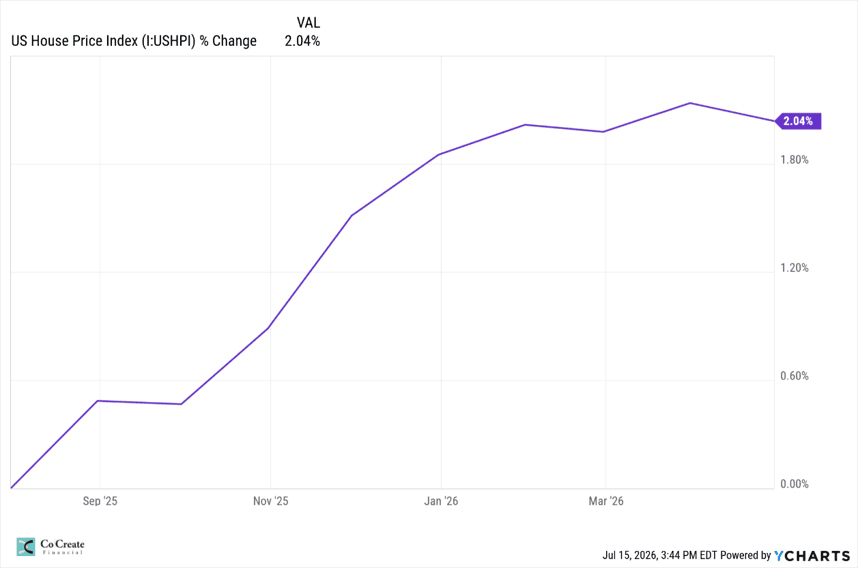
The state of the housing market is another popular topic often on the minds of many Americans. The U.S. House Price Index shows home prices continuing to rise at a modest pace, with annual growth of approximately 2.0%. While higher mortgage rates have made buying a home more expensive, limited housing inventory has continued to support prices by keeping supply tight. So, we’re in an environment where we can do one of two things: hope for rates to come down or build more! Although affordability remains a challenge for a lot of Americans, the steady pace of price appreciation suggests the housing market has found a healthier balance after the rapid gains seen in recent years.
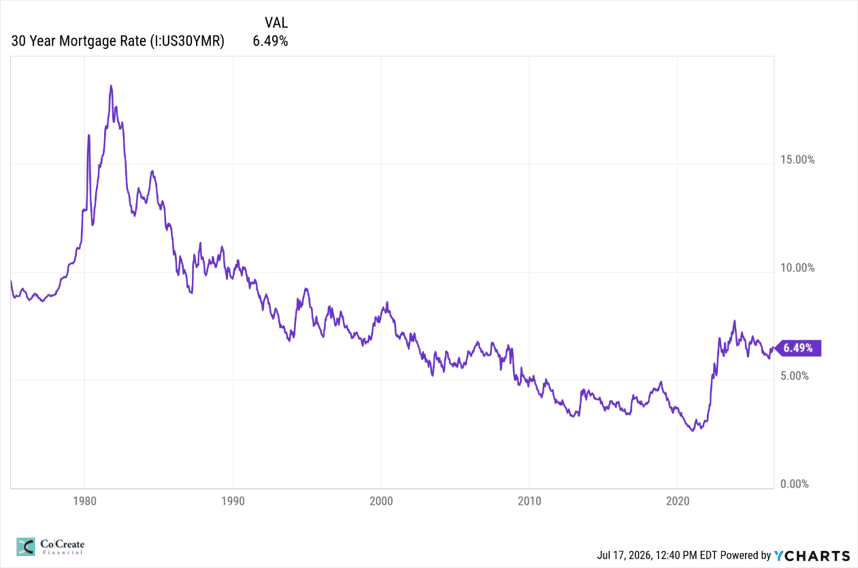
Additionally, mortgage rates of around 6%-6.5% are healthy and historically neutral. Current rates just feel high since we experienced dramatically suppressed mortgage rates after the 2008 housing crisis up until rates started to rise post Covid. The graph below shows how the 30-year rate has changed from 1975 all the way up until 2026, so when we take a more bird’s eye view, current mortgage rates are not in a crazy, rough place.
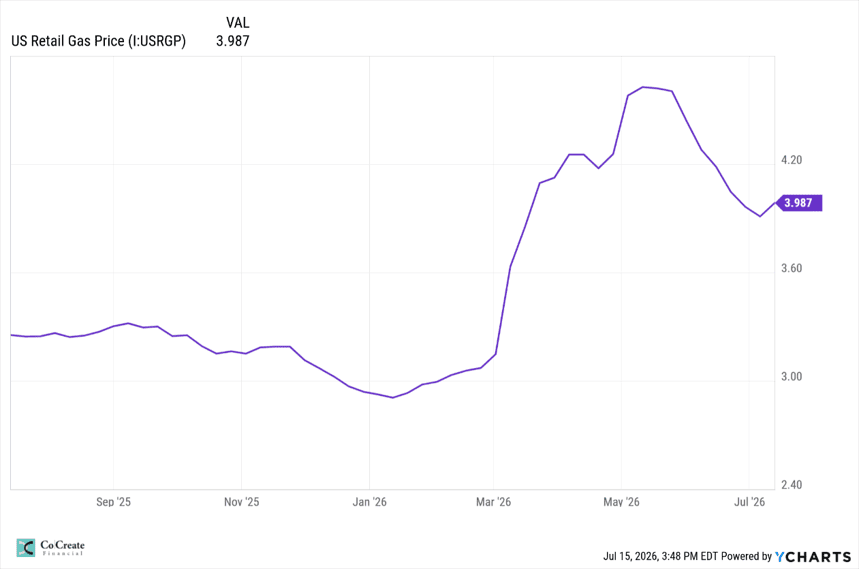
Along with inflation and the housing market, gas prices remain a major concern for many people. Looking at the graph above, we can see that the national average gasoline prices increased sharply this spring before easing slightly in recent weeks, with prices currently averaging around $3.99 per gallon. Gas prices are heavily influenced by crude oil prices, global supply, refinery production, and geopolitical events. Because fuel is a necessary expense for most households, higher gas prices decrease disposable income and can contribute to broader inflation over the long term, while lower prices provide people with more spending power.
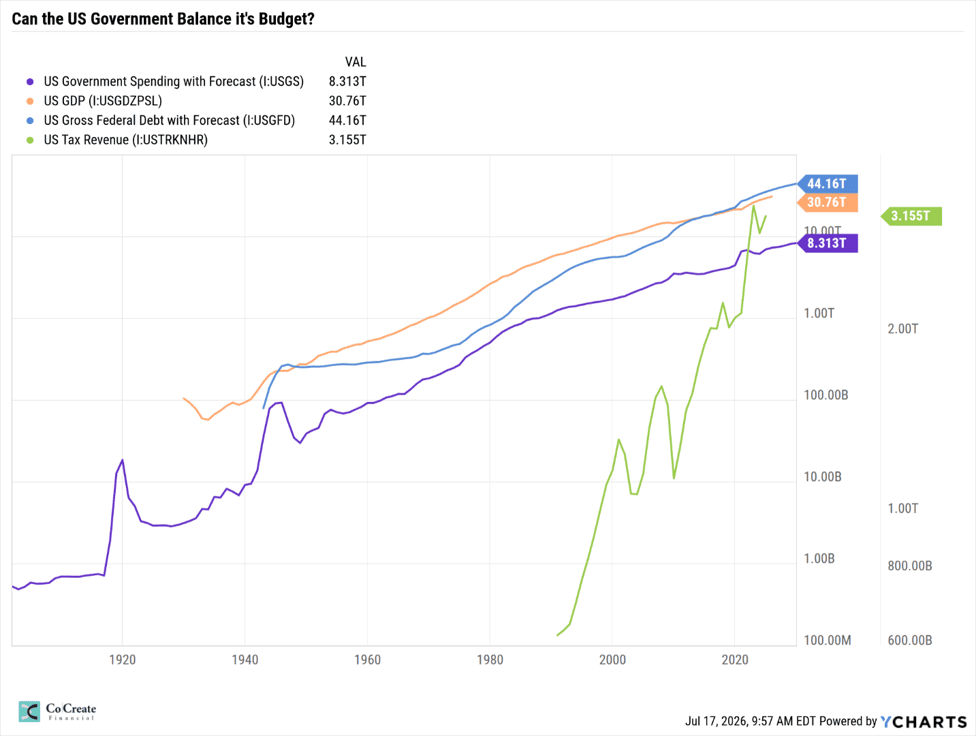
It is no secret that the United States government has a huge debt problem. This chart compares four key indicators of the health of the U.S. economy: government spending, tax revenue, gross domestic product (GDP), and total federal debt. GDP is the total value of all goods and services produced in the United States each year and is commonly used to measure an economy’s size. Ideally, as the economy grows, tax revenue also grows. However, government spending has consistently outpaced tax revenue, creating an annual budget deficit, which is the difference between what the government spends and what it collects in taxes. Those yearly deficits accumulate over time (and accrue a ton of interest), becoming the national debt we see today.
But what does this mean for investors? Rising national debt doesn’t mean the economy or stock market suddenly stops growing. It does mean that the government has less financial flexibility and will eventually have to make a choice between raising taxes or reducing their spending (hopefully they will not choose option C which is to just keep accumulating debt and interest). While there are unknowns about what exact strategy Washington will decide to take, it doesn’t change the significance of staying invested and focused on a long-term plan.
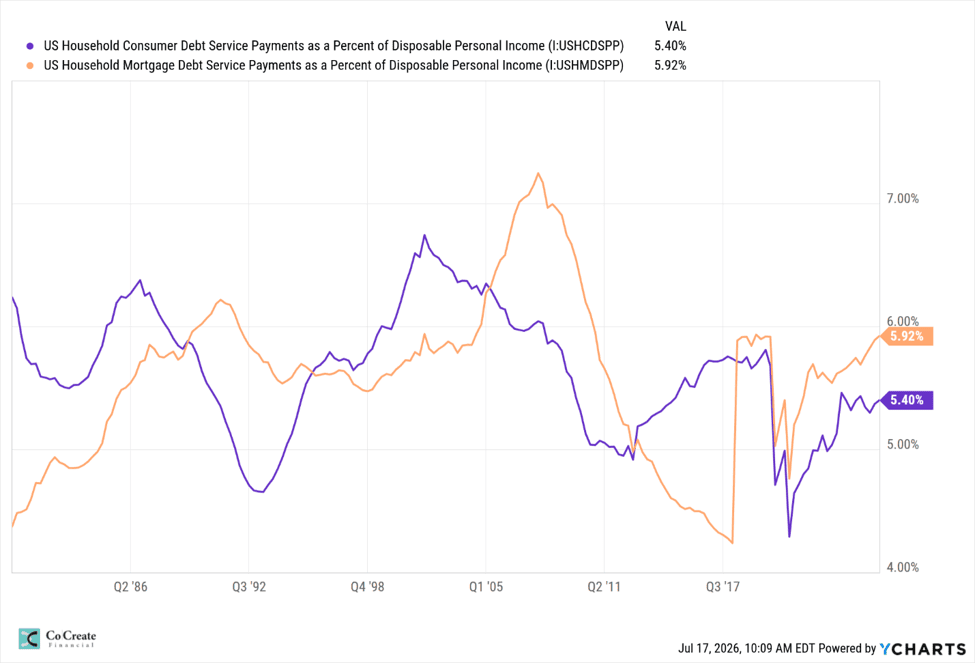
While we are on the topic of debt, let’s look at it from a U.S. household perspective. This graph offers a good illustration as to where we are at as a country on household debt levels by showing the percentage of disposable income (amount of money left after taxes) that U.S. households spend on mortgage payments and consumer debt payments like credit cards, auto loans, and personal loans. Despite higher interest rates over the past few years, debt service payments remain near historical averages. Much of this resilience comes from homeowners who locked in super low mortgage rates around 2020 and people who have generally maintained steady income growth. While financial stress certainly exists in many households across the U.S., the broader picture is relatively solid. One thing to note is that it is clear that that percentage is on an upward trend as more people finance purchases at today’s interest rates. While this is a trend worth watching over time, current levels suggest that, overall, U.S. households remain in a relatively strong financial position. As long as employment stays steady and incomes grow, household balance sheets should remain supportive of the broader economy.
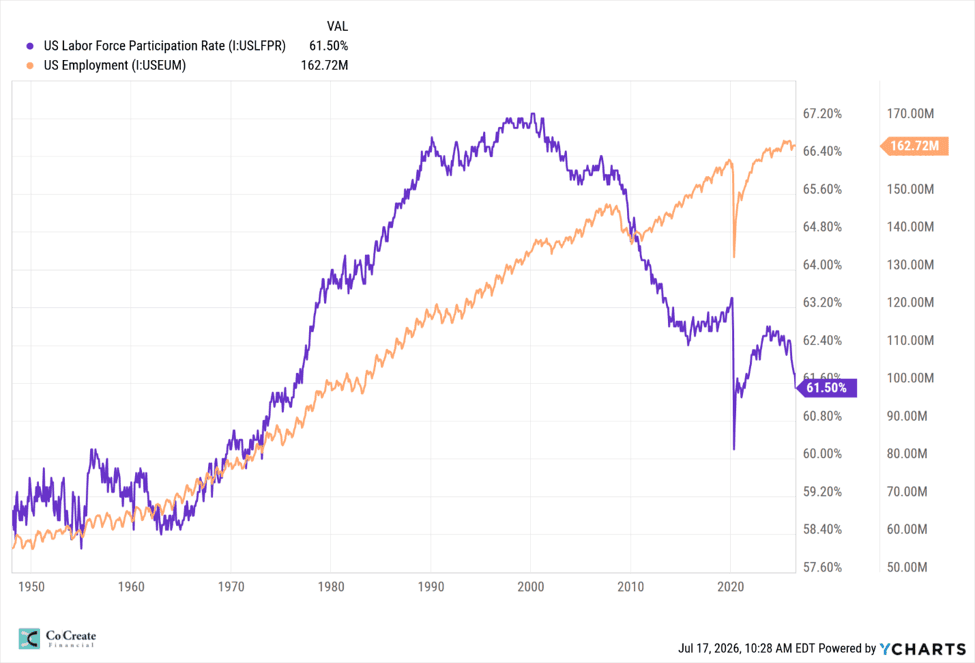
Speaking of employment, the graph above compares two different measures of the labor market: the total number of Americans who are employed and the labor force participation rate, which measures the percentage of working-age adults who are either employed or actively looking for work. While employment has recovered from pandemic lows, the labor force participation rate remains well below its peak from the early 2000s. In other words, there are more Americans working than ever before, but there’s a smaller share of the working-age population who are participating in the workforce.
Several long-term trends have contributed to this shift, including an aging population, increased early retirements, and, in some industries, a mismatch between the skills employers’ need and those available in the workforce. On the positive side, we have seen the number of unemployed workers and job openings fall relatively in line with one another on a national scale. Of course, there will be variations across industries and local economies, but broadly speaking, the United States has bounced back from the labor shortage it experienced in prior years.
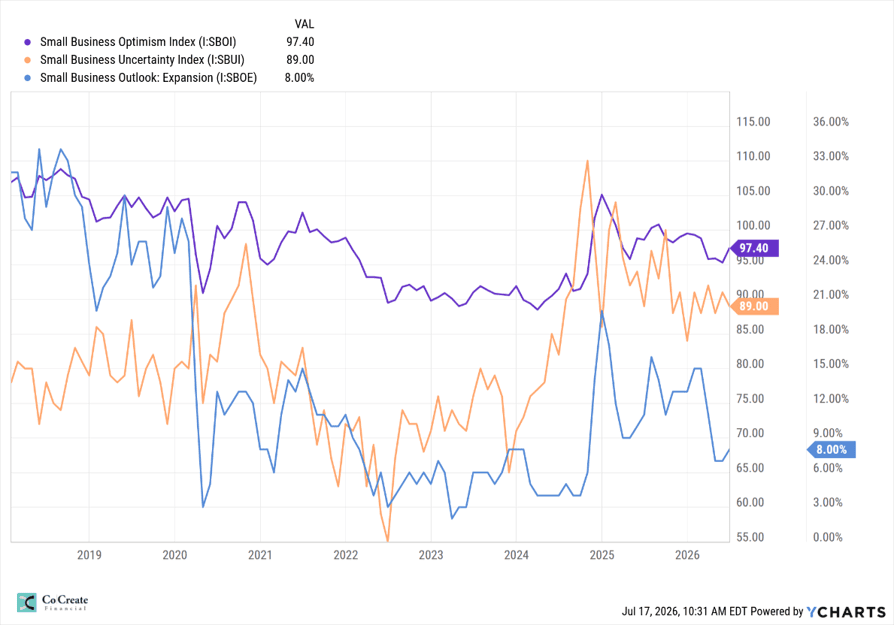
Small businesses are often considered the backbone of the U.S. economy, so their outlook can provide valuable insight into where the economy may be headed. This graph tracks three measures: small business optimism, uncertainty, and plans to expand in the future. While uncertainty remains elevated compared to past levels, optimism has begun to stabilize and businesses are once again showing a greater willingness to invest and grow. Although many business owners continue to face challenges such as higher borrowing costs and labor shortages, the overall trend suggests confidence is gradually improving, which is an encouraging sign for future economic growth.
One of the largest sources of headlines this year has been the conflict involving Iran and Israel. Investors are closely watching developments there since the Middle East produces a significant share of the world's oil, and disruptions to shipping through the Strait of Hormuz, one of the world's busiest oil transit routes, could reduce global energy supplies. Recent tensions have already contributed to higher oil prices and renewed volatility in energy markets. Higher oil prices can eventually work their way into inflation by increasing transportation and manufacturing costs, so it is something to keep an eye on.
Artificial intelligence has been one of the strongest drivers of stock market performance over the past few years, particularly among large tech companies. While AI could represent a transformational long-term opportunity, investors have recently become more selective as valuations have climbed to historically high levels. Rather than questioning AI's potential, the market is beginning to ask whether current stock prices already reflect years of future growth. Companies will increasingly need to demonstrate that heavy AI investments are translating into meaningful revenue and profits, not just speculative growth. I have no doubt that AI will continue to revolutionize innovation and continue to become more useful in daily life, but which companies will come out as winners is where the unpredictability lies.
One potential theme to watch in the coming months is a rotation from high-growth, AI driven tech stocks toward more value-oriented companies. When we think of value-oriented companies, we think of the businesses that are stocking our grocery stores, keeping our lights on, and supplying everyday products we rely on without a second thought. These are companies that provide essential goods and services you and I will continue to use regardless of the economic environment. As investors become more selective and question whether current AI valuations fully reflect future earnings potential, investments may begin shifting toward sectors with lower valuations, more stable cash flows, and established businesses. While artificial intelligence is expected to remain a powerful long-term growth driver, markets often rotate leadership as expectations evolve so we will continue to monitor if any major shifts start to emerge.
We’ve spent some time talking about the challenges in the investment world, but there are also many reasons to remain optimistic. As we celebrate America’s 250th birthday this month, it’s a fitting reminder that innovation, entrepreneurship, and resilient businesses have long been drivers of economic growth and prosperity.
While much of the market’s attention has been on AI, there are many high-quality companies out there with strong leadership, healthy balance sheets, and consistent earnings that continue to create long-term value for their owners and consumers. Corporate earnings have stayed strong, showing that success isn’t only found in a handful of dominating companies.
Artificial intelligence is also entering a new phase. Rather than simply generating speculative excitement, businesses are increasingly finding new ways to apply AI practically to boost productivity and efficiency. As adoption across sectors expands, opportunities may go beyond the companies developing AI to those using it to strengthen their business models.
While productivity gains from major technological advances can take years to fully materialize, history suggests that patient, long-term investors are often rewarded as innovation becomes more embedded across industries.
The challenges we’re seeing today are not out of the ordinary to long-term investors. Markets will always have ups and downs, and today’s environment is no exception. Geopolitical events and changing expectations around artificial intelligence may continue to create short-term volatility, but they don’t change the long-held principles of disciplined investing.
Rather than reacting to every headline, we believe it’s important to stay focused on what matters most: owning high-quality businesses, maintaining a strategically diversified portfolio, and keeping your investments aligned with your long-term goals. Taking a calculated diversification approach allows us to avoid putting all our eggs in one basket, helping create a more resilient portfolio over time.
History reminds us that patient investors have been rewarded over time. Since 2000, the S&P 500 has delivered average annual returns of roughly 8%. While long-term market growth is an important driver of accumulation, successful investing is about more than simply participating in the market. A thoughtful financial plan includes a well-designed distribution and liquidity strategy, ensuring you have cash available when you need it without being forced to sell investments during periods of market downturns. This approach helps make retirement income more sustainable while allowing the rest of your portfolio to remain invested for long-term growth.
Above all, we believe successful investing is about more than managing a portfolio, it’s about helping navigate what we can’t control with confidence and what we can with clarity. Markets will continue to evolve, but your financial plan should provide you with stability through every stage. We remain committed to helping you make thoughtful decisions, adapt when needed, and stay focused on the goals that matter most to you.
Summary: Matt Hudak AAMS®, CFP®, CEPA®, Financial Advisor and Chief Investment Officer of CoCreate Financial, explains why the answer to whether you should roll over a 401(k) to an IRA (or a Roth 401(k) to a Roth IRA) is almost always yes, despite widespread internet misinformation driven by financial industry liability concerns and unresolved Department of Labor rollover regulation efforts stemming from Dodd-Frank. He compares 401(k)s as employer plans—limited investment menus, payroll-only contributions, vesting considerations, and stronger creditor protection—to IRAs, which offer far more flexibility, broader investment choices, consolidation of old accounts, and the ability to receive coordinated ongoing advice from a dedicated advisor. He notes potential downsides of IRAs if self-managed poorly, highlights myths about 401(k) fee advantages, and encourages viewers to evaluate rollovers in their specific context and seek professional guidance.
2026.05.08 Podcast Episode 3
Matt Hudak: Hi friends. We're going to talk about a really important question that a lot of people come to us with, and there's a lot of misinformation about it on the internet. The question is, should I roll over my 401(k) plan to an IRA? Or should I roll over my Roth 401(k) to a Roth IRA? What are the pros and cons? How do we unpack this? So we're going to dive in and talk about that in this video today.
My name is Matt Hudak. I'm the CEO of CoCreate Financial and really excited about this topic. When we look at this, a lot of the conversation, a lot of the information that you find online, has really centered around liability protection for the financial industry.
Back in 2012, when they enacted Dodd-Frank, they put in a directive for the Department of Labor to try to regulate rollovers, like they regulate the 401(k) plans even after they're outside of the employer plan. And this process of developing these regulations then has been caught up in court and in all kinds of different iterations of it that have been overturned, that have been thrown out, that have been really just not very functional. And so the industry as a whole has said, "we're going to say we're not going to give any advice on this. We're going to tell you it's better to leave it in the 401(k)," because that's the political risk that's on the firms to mitigate.
And they say, "I don't want to deal with violating a rule that doesn't exist yet." So they're more focused on that than really giving advice that's in the best interest of the person with a rollover, you.
So when we look at it, we want to look at a few different things. And we do need to evaluate this carefully in your context, but the short answer is almost always yes. You should roll over your 401(k) into an IRA. And there are a few reasons for that, but let's look at some of the differences and similarities before we dive into why you should.
One of the main differences with the 401(k) and the IRA is the 401(k) is an employer plan, and your IRA is your own plan, and that means a few things.
The IRA is very flexible. There's a lot that you can do in it. There's a lot you can do right. And in a lot of ways you can improve. There are a lot of ways that you can also go wrong and misstep in an IRA, especially if you're managing it on your own and, and you're not somebody that's built up the knowledge and experience with investing.
You can make a lot of unwise choices that maybe the 401(k) would prevent you from doing, but the 401(k) also, as an employer plan, has more limitations within it, and it has fewer different products that you can have. It also vests, which means that some of the money that your employers contributed as a matching contribution may or may not be yours yet while you're still working for the company.
Now, if you leave and roll over to an IRA while you're not fully vested yet, you might lose that vested amount. And then if you go back to work for that employer again, you might have to start over in that vesting schedule. And how that works is probably a great content for another video 'cause we don't have the time to dive into that here.
But when you're looking at that mix, you want to make sure that you're not planning to go back to the employer in the relatively near future because that could cause some problems to roll it over. If you're watching this video, you probably already know that you have to leave your employer in order to do that.
Or sometimes you might have that provision if you're getting ready to retire and you're in your sixties. You can sometimes roll over that balance to kind of get you started in the IRA and make your process of retiring more efficient. They call that an in-service distribution. And some plans offer that, some don't.
But within the 401(k) structure you have higher contribution limits, but you can only contribute through payroll. And the IRA, you don't have quite as high a contribution amount that you can make each year. But if you're not making the contribution to the 401(k) because you're not employed with that employer, you can't make that contribution anyway. So, the 401(k) has a higher limit of liability from creditors. So that you can't have a creditor when you owe money to someone, they can't come and collect that out of your 401(k).
In the IRA, you still have a million dollars of creditor protection. So it's still a substantial amount if we're looking at that IRA balance. But if there's a debt issue, we need to look at that and make sure that we're cognizant of what that looks like in our strategy for doing the rollover. Okay. So the biggest reasons to do this rollover really have to do with investments and advice. So when you're doing your research, you'll see online things about investment fees being different and maybe being less or negotiated down in the 401(k).
This is really just a myth. It depends on plan to plan. But often what we do see in 401(k)'s is that they have very low expense funds that are often low expense for a reason, they're subpar, their performance isn't great. And the quality of management is not very high. And the way that they get sales as a fund is to get them into 401(k) plans so that people have these limited choice menus and they'll buy these funds because it fits a category.
And a lot of times, employers or plan fiduciaries say well, I can meet my obligations by choosing something that's low cost, and they limit their search to things that tend to be low cost, and having a couple of things that are in a different investment mix, a different type of sector or, you know, something might be global, something might be small and aggressive or whatever.
And they pair a few things, but they tend to look at costs and other features of these funds. And we end up with these subpar mixes. They're just not portfolios that a professional investor would put together. They just aren't, and there's not enough choice within the 401(k) plans oftentimes to meet, even if they are good, to meet an investor's needs to meet one of our client's needs. So we're looking at saying, well, what do we do here? We want to be mostly in U.S. companies that pay dividends and there's not even an option in the 401(k) for that. Maybe we'll go with something that's the S&P500 index fund when we're investing in the 401(k) instead.
But then the S&P 500 index fund is not actually a diversified investment. It's 40% large cap tech stocks, which right now happen to be in a significant bubble as we're recording this. So that's actually a high risk momentum investment. And the 401(k) plans don't have the ability to account for those types of risks.
Whereas in the IRA, we can do a wide spectrum of things. Now, you don't want to go from a limited menu of investments that probably aren't going to get you into a lot of trouble. In your 401(k) plan to an IRA that you're managing and maybe doing highly speculative things like investing in Bitcoin.
Or there are some ways that you can own real estate in IRAs that have some pretty massive logistical drawbacks that create a pretty intense risk for you if you're not very very methodical in how you've evaluated that. So there are things that you can do again to misstep in these IRAs if you are not careful, if you're managing them yourselves, especially because if you're working with a professional, they should know the things that are going to cause problems and be aware of those and how to avoid those things. But within that spectrum, within an IRA, you can also own dividend yielding stocks. You can own tech stocks, you can own bonds, you can own individual bonds, you can have funds, you can have ETFs, you can have really any kind of investment that's out there in some form.
And there are a few things that are outside of that scope, but they're not mainstream types of investments that you can't own inside an IRA. So you have a lot of choice and a lot of ability to manage this in a way that works and you can hire professionals to get ongoing advice and to really have a financial plan that's coordinated to meet your needs.
Whereas in the 401(k), some of them do now have like a one 800 number where you can call a certified financial planner professional to get some advice on what you're thinking. But that person that you're calling doesn't really know your situation, like a financial advisor that you're hiring that's in your community, that's engaged with you, that knows your kids' names and knows how long you've been married, that understands the community, the type of neighborhood that you're in, where you're going, what your business looks like, that knows your tax situation, your estate plan.
So you don't really get the same kind of advice in a 401(k) that you can get outside of that 401(k) when you're working with a professional advisor that's dedicated to you and has an ongoing engagement. And then the other thing is with IRAs, you can roll over your 401(k) from the job that you just left into an IRA.
You can roll over the 401(k) from the job you left 10 years ago into the IRA and you can keep your investments consolidated. And sometimes you can even save in other types of buckets, like other types of accounts. We talk about these things like buckets here at our firm 'cause we like to be simple and speak in plain English, but you can put it into an account that you can save in parallel to the IRA too.
You can save where you can access it before retirement. So there are lots of different things you can do, but you can keep everything in one place. If you do these rollovers, and you're not going to walk into your retirement era in life or your next chapter and say, “I don't know where all my money is. I know I had this 401(k) from this old job, but I don't know how to find it.” That's a common thing. Or you'll be coming in and saying, I found this 401(k) from 30 years ago that I didn't know was just sitting in cash and could have quadrupled over the 30 years or whatever it would be in value. Again, that's not guaranteed, right.
Performance has risks and all of those things, having an investment grow, but you didn't realize that it was sitting there in cash or maybe even an unclaimed property somewhere. These are common things that we encounter with people is that they've lost assets from the past and it actually has a significant negative outcome for the client. When we see those things happen, in most cases, sometimes you find a hundred thousand dollars and you say, that's pretty sweet that I just realized I had this money that had been growing since I was 22. And that was like that, that's awesome. But that's the uncommon side of it.
More often it's things weren't managed appropriately because you forgot about them. And so keeping things consolidated, keeping things in a place where you can get professional advice really has a dramatic advantage. And most of the information that you see on, you know, the pros and cons of doing a rollover are really oriented around satisfying this regulatory burden and the liability that's been put on the financial industry to try to tell you you should keep money in the 401(k)s because they don't really want to say roll it over and then find out that they had some requirement that they didn't check on a form or something like that down the road. So there's really been really poor advice on this over the last 15 years or so. So I really want to encourage you to think about that. The fees are generally very similar.
Anything can be compared. It's apples and oranges. You might spend a little bit more on one side or the other in a specific context. But compare all these things, get advice, reach out to us. We're always happy to talk to you about the actual implications of your decision and what that means and help you make that decision from a really grounded, rooted, wise perspective. I'm excited to talk with you about this. Give us a call. We're always available to help you make these decisions. And excited. Take care.
Summary:
Matt Hudak AAMS®, CFP®, CEPA®, Financial Advisor and Chief Investment Officer, and Christa Hudak CFP®, ChFC®, CKA®, Financial Advisor and Chief Planning Officer for CoCreate Financial, explain their approach to financial planning by aligning financial decisions with a client’s core values, beliefs, and convictions to create more long-term satisfaction than traditional math-only goal setting.
2026.05.07 Podcast Episode 5
Christa: Thank you for joining us today. I'm Christa. And this is Matt. And today we're going to be talking about how we approach helping you align your financial planning, your financial decision framework with the values that you hold dear, and how and why that's important to make you truly successful in the long term.
Matt: Yeah, and what we found is when you do this, you really have a lot more satisfaction in your outcome across the board. We've spent a lot of years kind of following a traditional approach to thinking about financial goals that's really just purely math based.
And what we found is that it doesn't really lead you to the most efficient outcome in terms of what you internalize. Oftentimes people are not saving enough and they feel afraid of the future, or they're saving too much.
And they're afraid to spend it when they really should be using that for something that's meaningful 'cause you can't take it with you.
Christa: And I'll just add like these conversations that what we're going to get into, they're where things really come alive and they're the hard part, because if you were to say, you know, I want to buy a house that's worth this much in this many years, that's just a math problem. That shouldn't be hard for us to figure out.
Especially as financial experts who can run the time value of money calculations. That's not a hard question. The hard question is "how do we get the goals right and how do we line this up well over time?"
Matt: Yeah. And when we're looking at this, we look at a few different things and traditionally this has been like we've talked about math-based calculations to say how much are you going to have when you're long gone? And how do you make it last for forever? And then just give it this pile of money to your heirs. And hope that they do things well with it that they live well, maybe even in a way that you didn't. And what we look at is there are really three different types of capital that we have to plan for at the same time.
The first one of these is your financial capital, and that's pretty obvious. It's your money, it's your debt, your assets, your house, your cars, your cash, your stocks, all the different things that you own. Your business, if you have a small business. This is your financial capital. It's the stuff we can measure and calculate.
We have to make a plan for that. We have to make it last. We have to help you deploy that in the present as well. The next thing that we have is your social capital. This is really your influence. This is the influence you have in your family, in
Christa: your community,
Matt: in your community, in your church, in your business, with your employees, with your employers. You have influence across a wide range of individuals.
How do you make the most of that? How do you impact those people personally? How do you leverage that as well to have more impact in your community and to live a life that's more fulfilling in your sphere based on your beliefs and values and convictions, which we'll talk about that a little bit later.
And the third type of capital that we have is sorry, I already said social capital, spiritual capital. And this is, what are the lessons these deeply spiritual things, that you want to pass on? What are the beliefs that you think are important that have shaped who you are? These look different for many of us. Our spiritual capital is very significant in our lives. We really value our spirituality and our faith, and it's a main driver for us. And we find that's true for most people of faith. But even if you're not a person of faith, you have this spiritual capital. How do you want to influence people on that deeply personal and spiritual level and shape those people?
What are those things that you can give? So when we're looking at these we don't want to save these up until you're gone. If you look at things like social capital, spiritual capital, it's really easy to see that it doesn't do any good if you just wait until you've passed away, and you've never been kind to anybody, or never cared or showed up for somebody, and you write them a letter after you've passed and say, you know you're going to receive this when we're at my funeral. It doesn't do anything. Right. It's obvious to us that those you can't pass after the grave, but financial capital is also something that you need to distribute and balance over the course of your lifetime. We don't want to see any of our clients starve in retirement, but we also want to make sure that our clients are able to live here and now and do the things that are meaningful and impactful all along throughout the course of their life.
Christa: And also, when we encounter people that have excess, you know, they've been good savers, they don't have extravagant lifestyles, and we're looking at the situation and there is in fact excess, we want to give them the opportunity to ask the question, how do I want to use this or distribute this during my lifetime, instead of just saying, well, they're happy with living on a lot less than their portfolio can generate, and it'll just go into their estate. But to give them that opportunity in the present as we assess things to say, what do you think the best choice of using this money is?
Matt: And it's a lot more fun to take that approach. So we really hope that we can engage these different types of capital along the way. And we use a values and beliefs filter to really help identify how that works.
Christa: Yeah. So kind of shifting to another place in this diagram that we'll have up on the screen, we have these concentric circles, and in the financial industry we tend to live on the outside of the circle and we want to talk about things like, you know, what's your family situation? Are you married? Do you have kids? Who are the people involved here? What do you do for work? How much do you pay in taxes? What other components are things that we need to fund or things that interact with the finances? And we tend to live just in that outside sphere of conversation. But what we find is that to really understand those things for our clients and to really drive forward on a holistic plan, we have to start at a much more core level, which is, what are your beliefs, values, and convictions, and how do those drive the things that are most important to you?
Matt: Going from that tangible outer circle to sort of almost through the circle that defines our passions to what's really at the core of those.
Christa: Yeah, absolutely. Because we find that this changes things and it also helps explain the things that are most important to us, and also filter out the things that maybe are not so important, and we can all come up with all kinds of goals, right?
And 'cause so often we just say, well, what do you want? And you're like, well, I can start spitting off some things that I think would be cool. And if you really lean into those, you'll decide that they're really important, and maybe they are.
But if we don't ask the question of why they're important, we can find ourselves going in the completely wrong direction.
Matt: Yeah. And whether those are career goals or recreation goals, travel types of goals that might be family, a family vision that you have, as we ask those questions of, well, what's driving behind that?
What's the driver behind that? What's the why? We have to do that even sometimes a few times.
Continuously. Yeah, continuously. And really, really dig. Dig down deep to say, you know, what are the pieces that aren't changing about this?
You know, when you get to the place of having that new house, what's still the same because once you get to your dream house, you have to figure out the next chapter and reinvent yourself. You have to have a new vision and a new dream. So there's something that has to be really more centered to align all of your goals so that you can be consistent and really achieve those things.
And one of the things I think that we found is a lot of these values, these beliefs, these convictions, these things that are core to our ourselves, they actually don't take a lot of capital.
They're often free.
Christa: Okay.
Matt: If you really care about having a healthy marriage, if that's a value to you that doesn't take money. Sure it's nice to go out to dinner or it might be nice to take a vacation with your spouse or do something. That's not to say that money can't add value. Your resources, if they're used well can bring some satisfaction to those, especially temporally.
But you know, in our marriage, we're married, by the way, if you don't realize that already. But in our marriage we get to spend time with each other. We get to work on our communication skills and we get to pay attention and actually look internally and say, am I valuing Christa? And that doesn't take anything. That's free for me to build good habits in our marriage and to pay attention. So, a lot of these beliefs and values and convictions that we find people have they don't take a lofty savings plan to get there to accomplish it. It's really about being disciplined and focused on the things that matter in the present, and then allowing the resources and the ways that you're using the capital to augment those and amplify your ability to be successful in those things.
Christa: Absolutely. And the other reality that we face is that goals are simultaneous, not sequential, and often in competition with each other. So, one of the things that comes up a lot that we see all the time is, you know, we'll have business owner clients who will have ideas or want to go on new ventures for growing their business, and they're really excited about those opportunities within their business.
And then they'll also say in the same conversation, and I want to spend more time with my family. And those are both very good things to be growing your business and spending time with your family, but sometimes they're in conflict with each other and that's just the reality of it. And there's no one size fits all answer to how to divvy that out or how to make that work.
But, to be honest, where we have to say we hold these values, and to get really real about what those are and what the most important things are, what the most important things are in different seasons, and be willing to say, okay, these values exist. These are the different things that I want to do. How do I align these up so that both can be accomplished when there is this tension of, you know, one seems to infringe upon the other?
Matt: And how do you reconcile that? To riff off that example, you might have a business idea that has a really positive impact in your community and that might be really, really important to you. And that might align with your values of having a really positive community impact of kind of, hopefully it's a little more specific than that 'cause that's pretty generic. But so you're looking at that, but you're also saying, I want to be there for my kids at this stage. Those are both really important and good things, and you might lean toward solving that in some sort of chronological prioritization structure. Or you might prioritize that by impact and say, well, I am going to go into work on the community impact and hope that's a good example for my kids.
That's social capital and spiritual capital that you get to distribute by giving a good lesson for your children. Or it could be I'm going to find a way to bring my kids along in that impact. And there are different ways that you can arrange that, but without identifying both the tension and then the value drivers behind them, you can't really reconcile those very well.
We find that this values alignment has so many different dynamics that it brings. Spending problems, those are usually heart condition problems. Those are usually, I want some to satisfy something that I don't feel like is being satisfied right now so I'm going to look at a thing to meet a need that I have that's really intrinsic.
And we get into these habits of overspending. We see marriages where people come in and they're not in alignment and they're having trouble talking about the finances. Well really, if we get these values alignment issues figured out, if we get them on the same page as one another on these core things, then the financial pieces start to fall into place a lot more easily.
And so we're able to work through those issues too. So this is a really powerful tool as we're going through and looking through this with people. We're really, really excited about the opportunity to walk through some of this journey with you. It takes a lot of work, it takes a lot of time.
We don't get to discover these things overnight about the people that we're working with. It's a long process of asking those why questions. So, we're really excited to explore this with you and to sit down and talk through these things, figure out what your financial capital looks like and your social capital, your spiritual capital, these beliefs and values and convictions, how these can drive your purpose, your impact, and lead you to a far more satisfied end result in your financial life as you go through your whole financial life.
So we look forward to meeting you here in our office and talking through this more.
Summary: Christa Hudak, CFP®, ChFC®, CKA®, Financial Advisor and President for CoCreate Financial, reframes overspending as a deeper issue than income or budgeting, drawing on her experience working with clients across a wide range of financial situations. She explains that both contentment and overspending exist at every income level, and that simply earning more money rarely resolves spending problems. Instead, Christa argues that overspending is rooted in unmet longings and dissatisfaction—a “heart issue” rather than a math problem. While practical tools like budgeting are important, she encourages viewers to reflect on the underlying emotional, relational, or personal drivers behind their spending habits. She closes with an invitation to honest self-reflection and open conversation, especially for couples, as a necessary step toward lasting financial health.
2026.04.10 Podcast Episode 4
Christa Hudak: Hi friends. My name's Christa with CoCreate Financial, and today I want to talk to you a little bit about the issue of overspending, and we're going to talk about it from a little bit of a different angle. But first, let me set this up for you, because as a financial advisor, I have the opportunity to engage with a lot of different people in a lot of different scenarios.
And there are some really interesting things that emerge, especially as we look at the concept of overspending and what that can look like in different scenarios. And I first want to start on the positive side, which is that I encounter a lot of different individuals at all different income and asset levels who are very content and do not overspend. It is truly incredible to me. Sometimes I encounter people with very, very modest incomes who don't feel like they need anything more, and often are saving significant amounts. And I have other clients who have significant resources and lots of income who who manage that very well.
And so we see people successful in their spending levels at a huge range of income levels. On the flip side, we see something very similar with overspending. Um, And this can look like accumulating consumer debt or maybe even just spending at a level that you're always a little bit behind. You know, maybe you don't have a mounting consumer debt issue, especially at those higher income levels.
But maybe there's nothing to save and even small things that throw you off financially and small little emergencies, like needing to fix your car, become a big thing because you don't really have any reserves, even though there's a significant amount of income. And what's interesting is that there's no income level where these things disappear and it's really easy to you know, take a look at your budget, take a look at your spending and say, hey, all I need is $500 more a month, or I need a thousand dollars more a month. But we consistently see when people have a spending problem that the increase in the money doesn't fix it. And that really should give us pause and say, what's really going on here?
Because if it was as simple as, you know, this amount of money is not enough. I just need a little bit more, a little bit more money should fix it. But that's never what happens outside of a different strategy. And that's why I want to posit to you today that an overspending issue isn't actually a math issue.
It isn't actually an issue of how you're organizing your finances necessary, though, that can definitely help and that can bring these things to light. The real issue is actually a heart issue, and it's a condition of what you're longing for and what you're chasing. So let's unpack that a little bit more.
When you are overspending, it's because you're desiring for something more and you're not connected with what's really going to bring you fulfillment. And so you're always looking for that in financial means, which is a pretty radical statement to say that it's not just as simple as I need more money and that's going to fix it.
But we know that can't be the answer because people continue to overspend even as they have significantly more money. So with this, if this is something that you're struggling with, no matter where you fall on the income spectrum, I would just encourage you to you know, first of all, do the due diligence.
There are so many, so many resources about managing a budget and not overspending. Do those things to evaluate what you're spending and how you're spending it, but then to ask the questions of what's really behind this? And why am I unsatisfied? What's going on in my heart, in my relationships, in my situation, that is driving my desire to spend money on things that I know I can't afford?
And to reorient yourself because this is not an issue that's just going to go away. It's not going to get fixed with making more money, and it actually gets a lot scarier as you make more money because you know when, when you're living on a modest income and overspending, you're going to have this mounting credit card debt, and that can is obviously very, very problematic.
But something happens as you get into higher levels of income, which is that lenders will give you even more. And more and more. And those things can snowball really quickly into actually significantly worse situations and more difficult situations to get out of. So I would just encourage you to ask this question, what's really going on?
And you know, if you're married, have a conversation with your spouse and start unpacking. The truth of why you are struggling with spending and that, and the recognition that it's not a simple math problem, it's something going on on a much deeper level. I hope this is helpful for you today and encourage you to just take the time to reflect.
I’ve seldom witnessed a time when information was so unreliable.
We spend a phenomenal amount of time and resources focused on understanding what is happening around the world that may affect the stock market and other areas of our clients’ financial lives. We’ve always employed an intensely disciplined approach to review sources from various perspectives, comparing headline reports to primary sources of information, and doing our best to identify and challenge our personal biases. What seems crazy to us, is that nearly all of the information we come across, regardless of the source, has been wildly skewed and is propagandized to one side or the other. Naturally you’ll read this first as saying the other side is spreading misinformation, but it’s your side too.
Misinformation is baked into the data as well. We’ve again seen more substantive downward revisions of economic data, and it feels as though politicians and pundits have realized they can blast the most miniscule (and often irrelevant) information in memes across social media to manipulate public perspective. Again, all sides are doing this and if we truly want to understand the world around us, we must look first at the ways our own biases and groupthink can cause us to misinterpret reality. None of this is even touching the new reality that AI can fabricate all kinds of believable fakes (I’m not claiming everything is a deep fake, but I have access to AI video and audio tools, and it is alarmingly easy to do).
So what then, can we believe?
Businesses are run by people who are carefully working to create products and services for people who need them, and they aren’t doing it passively. They adapt to consumer demands, changing costs, new technologies, and economic conditions. They have a profit motive, and the end goal is to reward their owners in the form of a dividend payment. So, we invest by owning businesses that have been successful at this for many years. When we have a long-term perspective, these types of investments work very well and eliminate the need to obsess over market timing (which always hurts more than it helps).
It’s important to have the appropriate amount of cash in your portfolio. How much depends a great deal on your personal situation, but insufficient cash can force you to sell investments at a temporary loss that you otherwise wouldn’t sell. In our portfolios, we manage this dynamically depending on the magnitude of potential risks we see on the horizon (as those appear more significant, we tend to have more cash in portfolios). Having the right amount of cash in a portfolio also allows us to take advantage of opportunities as they arise.
We can diligently diversify risk across various industries, business, and service models while avoiding low-quality and high-risk investments (“index” investing really diversifies the high-risk, momentum stocks with lower-quality investments you wouldn’t intentionally buy). We can measure our effectiveness at this in a granular way and pay attention to the specific business, political, and economic risks that could hurt the business (tariffs are a great example here). A tariff on a specific product may heavily impact one business and have a negligible impact on a business not impacted by that product. Investments aren’t all the same, so it is important to invest in them on their own merits. For CoCreate clients, we fully manage this process for you.
We can believe that the only way we can fix the challenges in our society is to begin loving our neighbor, especially those who are different from us. We can’t expect the pundits and politicians to stop exploiting our polarized perspectives. We have to fix that on our own, in a grassroots groundswell of love, forgiveness, and humility. So as you’re watching headlines about anything going on in the world, remember that if you expect the worst from people, you’re guaranteed to get it, but if you open yourself up to look for the best in people, you’ll be surprised by how much you’ll find.
Military Operations in IRAN
I hate war, but I also hate mass murder. I’m confident nuclear weapons are destructive, especially in the hands of violent people. I’m amazed that the most dominant conversation around the conflict in Iran has been about gas prices rather than the millions of people tortured and murdered by the Ayatollah over the past 50 years. We should all feel the gravity of many conflicting emotions about the events that are transpiring. We are praying for every human life and for true peace when the conflict resolves. I will do my best to keep my comments focused on issues that will affect the market and economy.
While we have little quality information to rely on, there are several key premises we should be able to rely upon:
We are presently watching the start of a two-week ceasefire. The basis of the ceasefire agreement is unclear across various sources, and we are already seeing officials talking about where or not it has been broken. We would expect to see some of this in a cease-fire negotiation, but it underscores the reality that, from a market perspective, we must consider the conflict to be ongoing until peace is sustainable for the longer term.
Extended Bull Market and Slowing Economic Expansion
You can measure bull markets (growing stock market) and bear markets (declining stock market) in a variety of ways, and different commentators will mark the start and end of a bull market differently. In short, the stock market has been growing ever since the bottom of the great recession in 2009.

It’s been an exceptional bull market driven by a technological revolution that has changed life as we know it. These tend to last about 17 years before there is a meaningful correction in the markets. This isn’t a rule, of course, but we’re on year 17 and there are a mix of reasons to be excited about the future of the economy and things we should find quite concerning. In both cases, you want to be meaningfully invested in the stock market, because over time, these appear more like blips on the radar than financial catastrophes (they become catastrophic when you try to play them to your advantage. Inevitably, you end up selling at the worst time and buying back in when it’s too late). At the same time, we are becoming more defensive in our portfolios as many industry-specific risks and broader stock market risks increase. The S&P500 (which most people use to represent the “stock market” broadly… we think that’s fallacious, but that’s a conversation for another time), looks like it is beginning to form a rounded top. This tends to happen at the end of these secular bull markets as people begin to become concerned about the prospects of future growth. When we do this type of “technical analysis,” we need to be careful not to give it too much weight because it could mean something, it could mean nothing, or it could look entirely different tomorrow. As we are looking at the broader spectrum of data, it can sometimes be helpful.
The end of this secular bull market also doesn’t necessarily mean an impending stock market crash. There are many scenarios (some of which already appear to be playing out) which could avoid a broad-based market correction. We need to be strategic here, avoiding the major risks while maintaining well thought out investments in businesses that have a real basis for their value (i.e. healthy/growing profits combined with a long history of rising dividends).

Data Indicates Strain on the Economy
Artificial Intelligence
We’re continuing to monitor the investment environment around Artificial Intelligence. In short, we’re still seeing an AI bubble. There is good and bad at this point (which is a slight improvement over only bad). The good news is that we are finally beginning to see AI implemented in ways that can yield significant productivity gains, while at the same time, protecting your own Intellectual Property and private data is becoming easier (I can train and run my own Large Language Model right on my laptop). As I see it, there are things AI will never be able to do, but things that AI can do exceptionally well. The most economically significant development at present is the ability to easily program custom solutions and/or integrations so that information and systems that have been cumbersome and fragmented can be accessed more efficiently across teams. I believe this will be the first wave of AI usage that creates widespread return on investment.
Despite the continued development of AI, the issues with investment in AI related business persist. Valuations (though AI stock prices have decreased, making values a little better than a few months ago), are still off the charts and demand massive new revenue to justify the current prices. The values are driven by a circularity problem with the major AI investors. JP Morgan analyst, Michael Cembalest, explained this issue clearly last October:
“Oracle’s stock jumped by 25% after being promised $60 billion a year from OpenAI, an amount of money OpenAI doesn’t earn yet, to provide cloud computing facilities that Oracle hasn’t built yet, and which will require 4.5 GW of power (the equivalent of 2.25 Hoover Dams or four nuclear plants), as well as increased borrowing by Oracle whose debt to equity ratio is already 500% compared to 50% for Amazon, 30% for Microsoft and even less at Meta and Google. In other words, the tech capital cycle may be about to change.”
Essentially, there are massive investments being made by the big AI companies and reciprocal investments being made into the big AI companies, all without the support of any meaningful profit from the AI-related activities. It’s been massive corporate FOMO (fear of missing out). We still need to see enough revenue coming from AI business to justify investment in AI at the present time. Without that revenue, there is no basis by which we can expect anything but an AI crash.
Finally, the AI hyperscalers have been buying immense amounts of computing power (chips, data centers, etc.). Much of this will need to be replaced in the near future. According to McKinsey & Company, hyperscalers need to generate an additional $750 billion by 2030, just to account for the depreciation of this equipment. The combined profits of the hyperscalers are approximately $450 billion at present. These companies that are experiencing extreme values from the circularity issues also have a massive impending financial hurdle to overcome. Either the profits start showing, or the prices must come down much further so that they reflect these companies’ actual values.
Again, every business is not in crisis. We own many in our portfolios that are wildly profitable and are valued fairly (or even cheaply). We believe that now, more than any time in the past ~15 years, careful, intentional, long-term investment in profitable, dividend paying businesses matters. This simply can’t be accomplished by “index” investment, market timing, or many other common approaches. We are working hard to keep our client's portfolios profitable and prepared.
2026.03.16 Podcast Episode 2
Matt Hudak: Hi friends. My name is Matt Hudak. This is Christa Hudak. If you haven't had the chance to meet us, we're really excited that you are exploring CoCreate Financial and checking in on how we invest. That's what we'll be talking about today in our video. Just a little bit about our investment philosophies, how we approach each client's asset allocation, all those different things.
I promise we'll do it in plain English and it should make a ton of sense and hopefully inform your decision and our exploration process so that when we connect in person, we're able to focus more on the specific questions that you have, and less on just us talking at you about investment things that you probably don't even care about all that much.
So we're going to dive in and kind of talk about how we structure this.
Christa Hudak: Before we get into the specifics of talking about investments, the first thing we want to take a step back and consider is how we view a financial picture and making sure our clients have a setup that leads to their financial freedom.
And when we do that, you know, the very first base level that we always make sure with all of our clients is that they have appropriate cash reserves and then we bucket their assets. And this works both from the standpoint of cash management, of cash flow management, of just your regular income and also with your investment assets and how we approach it.
And we have this graphic that will show up on the screen as well that's something we use as we have this exploration for everyone. And the first thing that we always want to consider is that your basic needs are being met, right? So that you're paying your mortgage, you're able to eat reasonably, you're covering all the necessities in life.
And this is, like I said, true both for cash flow and then also when we're doing long-term planning and retirement planning, is that we really want to protect the chunk of your assets. And pay special attention that your basic needs are met throughout your life. But the reality is everybody, most everybody wants something a little bit more than just the bare minimum.
And we call that your adventure bucket. And this looks different for different people. Maybe it's living in a little bit nicer of a house or going out to eat or travel plans or all kinds of extravagant, fun things that we enjoy in life.
Matt Hudak: Yeah. It's the extras.
Christa Hudak: Yeah. That you're like, oh, I don't need this to live, but this is the thing that makes life fun.
And so we want to make sure we cover your basics. And then we also want to make sure that we're covering things that accomplish the things that you want to do in life. And somewhere in that range, there's what we call like enough. Sometimes people will talk about it as like a financial freedom line or a financial finish line of this recognition of, hey, I can be content at this level and satisfy the things that really matter to me, but that doesn't mean that that's all that there is to do, or maybe you have resources that exceed that. And so sometimes there's more adventure to be had. And then we also look at this idea of an impact bucket. And this can be the crazy projects or maybe it's a lot of gifting to family members or maybe some generosity of charitable giving.
Matt Hudak: Yeah, it might be pursuing business growth, a lot of those different pieces. So what does that look like in terms of when we're looking at somebody's assets, how much do we typically see in terms of need with that, like covering the basics to produce income, to cover your basic needs, what might that adventure bucket then look like beyond that?
Christa Hudak: Well, to be completely honest, this is very unique for everybody because we see a wide variety of just lifestyles and what people engage with and also different setups in it. There's different components in this that adjust those numbers both from the standpoint of what you are going to consume from it.
Maybe you just tend to live a simpler lifestyle and are very content with that. Or, also other income that comes in. So depending on what social security income looks like, or if somebody has pension income. The needs for those assets in that bucket to cover the basics goes down, but typically we see the basics and a little bit of adventure included when we have clients in the one to two million range with some additional income like we talked about. That's pretty typical.
Matt Hudak: Awesome. Yeah. And we'll fund that basics bucket typically with a portfolio of you know, dividend yielding stocks. We might fund that with some fixed income. We'll talk about what those things are in just a moment, but we'll look at really liquid, really secure things within the adventure bucket.
We'll probably look at more things like real estate rentals, those types of investments, they might be really stable income, except they've got some concentrated risk. You know, something goes wrong and the tenant doesn't pay. It's a big hit. So it's like they work well, but when they don't work, they really don't work for a period.
So we don't want to take those risks with your basic needs. But some of the adventure bucket, those [00:05:00] things kind of come into play there. And then in the impact bucket, we're looking at private equity and some impact investing sometimes like that. Things that can really do good in the world, solve hunger problems or human trafficking issues and make a profit at the same time.
So we look at all those different pieces but as you go up in those tiers, across those buckets, you have the ability to take some more strategic risks to accomplish great things because you're not needing those. But we also want to protect what you really need. So when we're doing that here's kind of what it looks like. There are a couple fundamental philosophies that we really hold to. We take a very business-minded approach to how we invest. So when you're looking at an investment with us, what we're doing is we're thinking about it like the business that we own.
The business that you, if you're a business owner and you own a business, we're thinking about the same way you would think about buying an individual business or making an individual loan or doing something like that. We make sure that we're really making smart decisions. The second thing that we've done is we've really taken a philosophy that clears [00:06:00] away a lot of the clutter from the complex investment products and the investment theories that really haven't added a lot of value to our ability to create returns in a portfolio.
They've added a lot of complexity. Some of them have added things that actually create new problems that we didn't have to deal with before, those types of theories. So we really take a very clean and simple approach that makes a lot of business sense.
Matt Hudak: And then we use a discipline process with that, and it allows us to maintain a laser focus on every investment that we own across our whole entire client asset base. And it actually allows us to measure things like diversification. It used to be that diversification was just owning everything and seeing what worked and what didn't, and you just kind of offset different types of things very generally, and it was a very kind of shorthand approach.
We take a very focused strategic approach where we can put numbers to this, and we audit that every month and debate that and discuss that as a team to make sure that we're appropriately managing our [00:07:00] client accounts at an investment level, at a very granular level, and we can specifically evaluate because of that, the specific business risks, the specific investment risks that exist with each investment, rather than just trying to monitor, you know, up and down fluctuation at the pricing in your account.
What's the actual risk that you have in that investment? What's the actual reward and how do we mitigate those strategically on a one-on-one level with each investment?
Christa Hudak: So Matt, do you want to back up and kind of show us how we view investments at their core?
Matt Hudak: Yeah, absolutely.
And we'll focus if it makes sense, we'll focus on just kind of this basics bucket, this more liquid style. When we get into the individual real estate properties, the private investments that someone might make, those are so individualized and they're so different from one to the next that we have to take a very focused approach in the context of our meeting, if that's you, but the first couple million dollars, like where we went, we were talking about will be in this basics bucket. So I'm going to go [00:08:00] ahead and pull up a whiteboard here and share this with you.
And kind of go through how we think about investing in general. So when you are making investments, it's not really owning markets or indexes or averages, it's not complex. It actually boils down to two things and there's kind of a third. That's the real estate side of things, but it fits kind of into the business ownership concept that we'll talk about.
The first thing that you can do is make loans.
I'm going to hold this because it's bouncing a little bit. So you can make loans and the other thing that you can do is you can own businesses. Own businesses. There we go. So when you're making a loan to somebody, I want you to think about this a lot like you're lending money to a friend. If you've done that at some point, or maybe even somebody that's not a friend, a random stranger, I don't know, that's one of the questions you have to ask.
If you're making this loan, think about what you're going to ask this person that you're lending to. You know, do they have a source of income to pay it back? What's the loan for?
Christa Hudak: When do they say they're going to pay it back?
Matt Hudak: Yeah. When do they say they're going to pay it back? Are they going to pay you interest?
Have you ever lent them money before? What do they do with it? Did they pay you back? All these questions we evaluate when we're looking at making loans as an investment. The only difference is you're making these investments to usually large corporations, governments and you're evaluating that on a case-by-case basis.
It's very different to make a loan to the city of Detroit than it is to the United States government than it is to Nigeria or to Coca-Cola. So it just depends on that mix. And we have to ask these questions. So what happens when you're making these loans is let's say it's the city of Bozeman, since we're located in Bozeman, and we're going to create an imaginary scenario here.
So the [00:10:00] city of Bozeman wants to lend money and they say, you know, if you give us a thousand dollars, 'cause they'll go to the public and do these incremental loans. So they'll say, if you give us a thousand dollars and let us keep it for 10 years, we're going to pay you a thousand dollars back in 10 years.
And that sounds like that'll work pretty well for, you know, keeping your thousand dollars stable. What I'll say is this thousand dollars, 10 years from now, isn't worth what a thousand dollars well by today it's, you know, a movie ticket used to cost and nickel kind of concept.
Christa Hudak: And Matt, what are they using this money for?
Matt Hudak: I don't know, maybe another high school. We could use a third one here in town.
Christa Hudak: Probably.
Matt Hudak: Yeah. So, in return for this, where you're going lend them the money, they're going pay you, let's say $60 a year. Okay? So that's 6% interest. If you're like me and struggle with math from time to time.
So, they're [00:11:00] going pay you $60 a year and that's going continue each of these 10 years until you get your principal back. Well, let's say in two years you want, and I don't know if there are 10 tick marks here, by the way, so don't count that. But if say in two years you need your principal back 'cause you want to buy a car or you want to do something fun, whatever it might be.
Well, if you go to the city of Bozeman at that point in time, they have no obligation to give you your money back. So they might just tell you to kick rocks. In fact, that's kind of generally what happens. So there's a system where if you want your thousand dollars back, you go out to the general market and it's a format.
It looks a lot like Craigslist but existed way longer than Craigslist has. But you go to this system where we post this for sale and then somebody says, yeah, I want that loan, or I don't want that loan. And what happens when you do that is if the city of Bozeman instead of $60 is paying [00:12:00] $80 now, well the person that's going to buy this from you is going to want, you know, to get a little bit of a discount on the price because they can get more interest if they just go straight to the city of Bozeman. And the opposite is also true. If instead of $60, they're paying, you know, $50. Then you're going to call and you're going to know that, then you're going to call the city and find that out, and then you'll end up offering to sell this for a little bit of a profit.
And so these prices, we call these bonds by the way. We try to avoid the jargon when we can. So in this mix, these bonds that these loans that you make move the opposite direction of interest rates. So when interest rates rise, the price of the bond goes down and when interest rates decline, the price of the [00:13:00] bond goes up.
So we believe that these investments work as they are, right? They're great. If you need to get $60 a year and you're fine with the thousand dollars being worth a little bit less because of inflation and ten years from now, that's a phenomenal product. It works really, really well. It's stable. Some of these are secured too against property. That's why there's a little bit of a myth, but that's why bonds are seen as more secure than stocks.
Christa Hudak: And you have a specific contract of how much you're going to get.
Matt Hudak: Yeah. And so you get some protections that can exist within those from default risk and stuff like that.
But within this it works if you're going to own that as an individual investment for that period, and you're comfortable holding it until it matures. A lot of times what we see though is these are held in funds for people and if you have a bond fund in your portfolio, what they're actually doing is they're often trading those bonds so that they can [00:14:00] get some extra yield.
So maybe they can make a profit as interest rates are declining and they have to also create the fund, the money to liquidate and to pay people out when people want to pull money out of their funds. And so there's some functions where a lot of times they're trading these bonds to make a profit rather than owning them for the interest.
And it creates a scenario where it's really almost just as much of a day-to-day fluctuation as the stock market, it's not the same amount of volatility if you measure it in a percent, but it's relative to what you're getting out of the bond. It's actually pretty similar, and they don't necessarily move in an opposite direction when you really need 'em to.
Christa Hudak: Another thing that we frequently see, as Matt discussed earlier when you are evaluating making a loan to somebody, you want to know whether or not they're going to pay you back, and that should impact the interest rate that you're going to get in receiving that if you feel like something's not very likely to pay you back, you might say, hmm, to compensate for this risk, I need a higher rate of return.
And one of the things that we frequently see [00:15:00] as we look at portfolios is where people hold bond funds that are specifically labeled high yield bond funds. And another technical industry term for that is actually junk bonds. And what these are is low quality, below investment grade loans that have a high risk of default and not paying on them.
And so they're able to get a much higher yield and well, sometimes it works well, but there's also a risk that those stop being paid, so they tend to be less secure as well.
Matt Hudak: Yep. And we kind of look at yield as interest rate, and that's another jargon term that we often use and sometimes, or avoid, it's basically like a rate of payout.
So, in this case, it's the interest rate that you receive from the bonds. So the higher the interest that you get, the more risk there is of default and other issues with the bond.
Christa Hudak: So Matt what's the other side and owning businesses?
Matt Hudak: The other side of this is owning businesses. You read my mind. It's underlining it right there. And owning businesses really [00:16:00] this is the function of the stock market. It was what it was designed to do. It was a way for you to own a tiny fraction of a large business and have the right, a lot of the rights of an owner, the rights to vote, rights to profits, all of that from the business.
And so when we look at the stock market, rather than trading the stock market day to day to get price, like price increases and get a capital gain here or there and take profits from it and maybe make money, maybe lose it, rather than treating the markets like a casino, whether that's day to day or on a longer, slightly longer term basis. We look at it as a way to own a business that you would want to own. And you can think about that a lot like owning a taco truck. This is my favorite analogy 'cause I love tacos, but it always makes me hungry. So tacos later! When you're owning a business, and just by the nature of kind of how our industry works, we're not going to talk about the specific companies, not because we're not happy to share how we do this in specific terms, but I don't want to lead you on that. You know, a company we're [00:17:00] going to talk about specifically is a good investment and then a year from now have something change and have you watch this video and then try to replicate what we're talking about and have it not work. So, we're going to talk generically, so you're going to own a business and there are so many of these, think about any of the corporations that you've seen and maybe you can put a placeholder in. When we're looking at this business, they've divided it up and it might be into millions and millions and millions of fractions, and you're going to want to own this little piece of it.
And so the company sells products. Maybe they make deodorant and personal care items or whatever.
Christa Hudak: Or maybe they make tacos.
Matt Hudak: Or maybe they make tacos. And you're going to get a portion of that earnings in the business, they're selling products like tacos. So if you're going to buy this taco truck, right, and let's say you're going to buy the whole thing because it's a taco truck and it's not a major corporation, but you're going to buy the taco truck. What questions are you going to ask?
You're [00:18:00] going to ask, you know, what does it cost to make a taco. What do beans cost? Do I have to hire people to run this or am I going to run this myself? Do I have old debts that I have to pay off? Will I have to finance the taco truck? Do they have a retirement plan where there's going to be obligations coming up? What's kind of the makeup of this? You're also going to ask, do people want tacos?
Matt Hudak: And I think we all know the answer is always, but when we're looking at this, we're going to look at the details of that business. And at the end of the day, no matter how much I love tacos, and hopefully you have a feeling for that at this, at this point, that no matter how much I love tacos, I can't buy the taco truck if it doesn't pay me at the end of the day.
That's the fundamental nature of business ownership is that it has to pay you a paycheck. If it doesn't, I'm better working a real job and going and getting tacos.
Matt Hudak: So from that standpoint, we have to look at these major corporations from that same lens. And when we do [00:19:00] that, it's really shown to work when we test this throughout history with less risk than most other things and more return. And that relationship looks really attractive when we just take the simple approach.
Christa Hudak: When we're looking at businesses in the stock market, one of the things to remember when we talk about risk, we're really talking about these fluctuating values.
And that's really the thing that causes some stress, right? In stock market investing is how much fluctuation do you see? So we always think of it as a good thing when we can get the return that people want to see, but also make those fluctuations less dramatic.
Matt Hudak: Yeah. And so this really works well for it. And not all businesses that you see that are listed on the stock exchange do this. Not all businesses that are listed on the stock exchange even have a profit. You would be amazed at how many companies are actually hemorrhaging money and people are investing and paying more for them, thinking, you know, they're going to be the future someday.
But if you looked at it as a business that you were going to buy to [00:20:00] run yourself, you would turn and run away. It just is not a good business to own and we don't believe in doing those kinds of things. We like to own good businesses. So let's say this business that we're talking about that brings in $3, whether it's a taco truck or
a tech company.
Christa Hudak: $3 for each share.
Matt Hudak: Yep. For each share for each one of these fractions that you might own. So it's bringing in $3 and in that it's going to pay out or we're going to want to see it use a dollar. And this is approximate. Let's say it's going to keep a dollar in reserves because it might need to build a new factory or they might need to do something with it. Create a new product or do research. So they're going to keep a dollar. We want to see that stability going with them. Lots of free cash flow, cash reserves, but they're also going to do something magic, and they're going to pay a dollar out to you as an owner.
Matt Hudak: And we want to see that. If a company doesn't do this, it's a sign that the company's not really mature in its development yet. [00:21:00] And there are a lot of investment arguments where you can say, well, maybe is that spigot? This is a spigot. Yep. There are a lot of arguments that say maybe you can make money on that, but it's not really assured.
Matt Hudak: Like you don't know until it starts coming out. So we're going to put a spigot on here and then what we'll do is we'll say this is paying a dollar, and maybe for the last 80 years this has paid a dollar out to its shareholders or maybe it's increased it for 80 years and has paid it out for a hundred.
We want to see this income coming in consistently and rising. That means market crashes happen. It's probably still coming in.
Unless there's something truly catastrophic with the company. And we can see that hopefully from develop and build from a little ways away if we're looking carefully.
But it's paying a dollar this year and then, you know, next year, because it's always does this, it seems or almost always does this increase, it might pay you a $1.10 and then the next year it's going to pay you a $1.30. That's [00:22:00] actually tangible value to you. You can understand what that is. That's $3 and 30 cents.
Christa Hudak: And Matt, how is this amount that's paid, determined?
Matt Hudak: This is determined as a flat dollar amount by the board of directors of these companies every year. So they sit down and say, we're paying this. It's not a percent. We'll talk about this as a dividend yield. It's what we call it. And it's paid out by the board of directors. So what happens is they don't look at this as a percentage. They look as a flat dollar, and they're going to pay that, and so we hope to see a pretty good dividend on most of the companies that we own. We really like to see about about 3% or so.
Where you get this good consistent income, and that's what gives a business its value. It's the paycheck that you get, and when we're looking at it, we're able to say, you know, this $3 and 30 cents, because it's going to continue and there's a little bit more math than just simply adding it up, but not much.
This gives a business value. It gives us an enough value we can [00:23:00] appraise this business for and say, you know, it's worth it to buy this business. And we might say, this business, we will pay $50 a share is a fair price to pay for that cash flow that we're buying. And knowing that if that continues and that cash flow continues to grow, we might be able to sell it for $55 in a few years.
And that's pretty stable. If it goes up to 70 and skyrockets, we won. If it just kind of plods along, then we're still really happy. And so it gives us the ability to manage this with some reason to believe in it. And if it things go down and the market crashes, and we can probably pull this illustration down now at this point.
So we'll pull this off and just talk to you. When we're looking at this, when the markets go down then, it also mitigates a lot of risk because there's cash coming in. So not only do you have a reason to say this company has a fair market value, even though it's on sale
It's going to continue to be consistently performing over the long term, and we have a good reason to believe that. It also means that we get cash coming [00:24:00] into your portfolio on a day-to-day basis, or on a month to month basis, where that cash that's going to come in is going to be able to buy shares at a lower price or distribute cash where we don't have to sell things at a loss or at a lower value for your cash flow needs.
So it really stabilizes the portfolio too.
Christa Hudak: Yeah, we view this as a great way to provide a lot of stability and also remember that there's a basis for the value of the investments that you hold. We hope that this has been helpful for you as you explore these concepts and look forward to having a conversation with you soon.
Hi everyone! This is my first time sending out an annual market review, and I am excited to share it with you all. As we leave 2025 and enter 2026, we all at CoCreate are feeling energized and hopeful for what’s to come.
Financial markets do not move in straight lines, and 2025 was no exception. While the year had its ups and downs, it also offered valuable lessons about patience and long-term thinking. In this review, we will take a closer look at the key events and major themes of the year, and what we believe matters most moving forward.
As we move into 2026, our focus remains on being thoughtful stewards of your investments. In a year shaped by uncertainty and change, we believe careful decision-making matters more than quick reactions. Markets will always react to headlines, but long-term success comes from staying grounded, patient, and intentional.
Rather than chasing trends, we emphasize diversifying your investments among businesses that are well run, have highly profitable goods and services that people want, and that pay you cash in return for your investment. This approach helps protect portfolios during periods of fluctuation while positioning them to grow over time.
At the end of the day, markets will continue to evolve, headlines will come and go, and uncertainty will always be part of investing. Our role is to help you stay grounded through it all by making thoughtful decisions, staying flexible when needed, and keeping your long-term goals in the center stage. By focusing on what we can control and being wary of what we cannot, we can look forward to the next year with clarity and confidence.
I have gone into more detail below and would be happy to answer any questions you may have.
I hope you have all had a wonderful close to your 2025, and I’m looking forward to meeting with you and having a great 2026 together.
- Emma Shaw
Inflation stayed in the spotlight throughout 2025 as investors and policymakers tried to figure out if rising prices were truly beginning to come under control. The most common way to track how quickly prices are increasing is by looking at the Consumer Price Index (CPI), which measures the cost of everyday items like food, gas, housing, and medical care. When CPI goes up, it means things are getting more expensive, and when CPI goes down, it means price increases are starting to slow.
At the start of 2025, CPI inflation was around 3%, which is higher than the Federal Reserve’s long-term goal of 2%. By the end of the first quarter, inflation cooled to around 2.4%, which was a positive sign that pricing pressures were starting to let up. However, progress was not linear, and CPI moved back up to roughly 2.7% by mid-year and hovered close to 3% again by early fall before going back down below 2.7%.
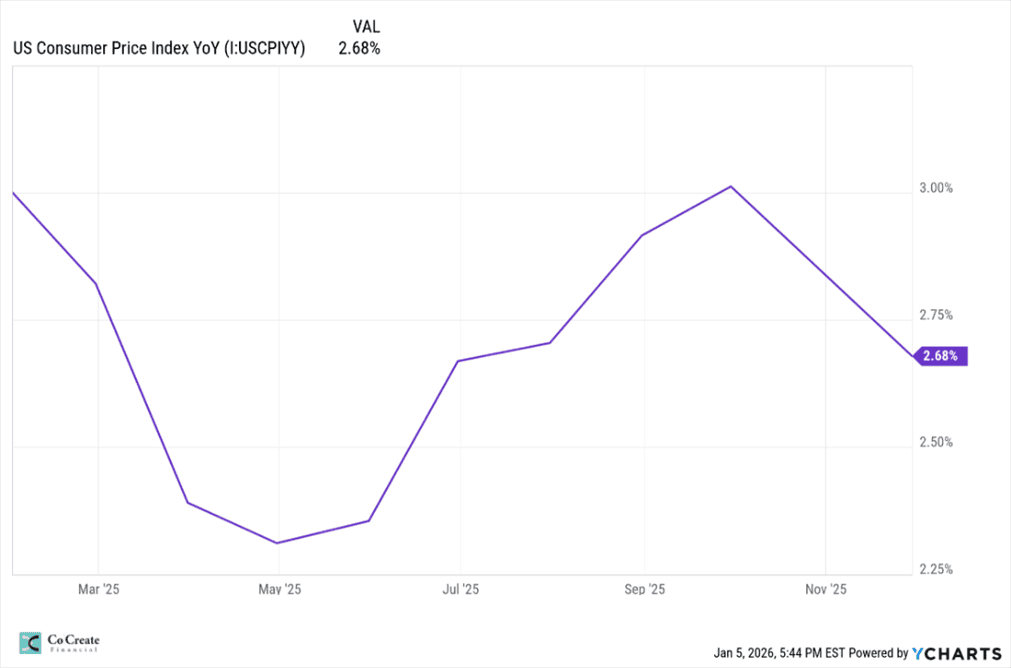
The graph above tracks CPI inflation over the course of the year. The line moving down means inflation is slowing, while the line moving up means inflation is picking back up. This back-and-forth pattern we can see explains why inflation continued to feel frustratingly “sticky,” even when some areas of the economy improved.
But the uneven path of inflation in 2025 is not a complete surprise, inflation rarely dissipates quickly, and expecting a smooth decline is not totally realistic. It’s normal for progress to stall or even reverse temporarily, especially when wages and housing costs remain elevated.
For investors, this backs up the importance of remaining patient and not overreacting to shorter-term data. The stabilization process is complex, made up of many various interlocking elements that move at different paces.
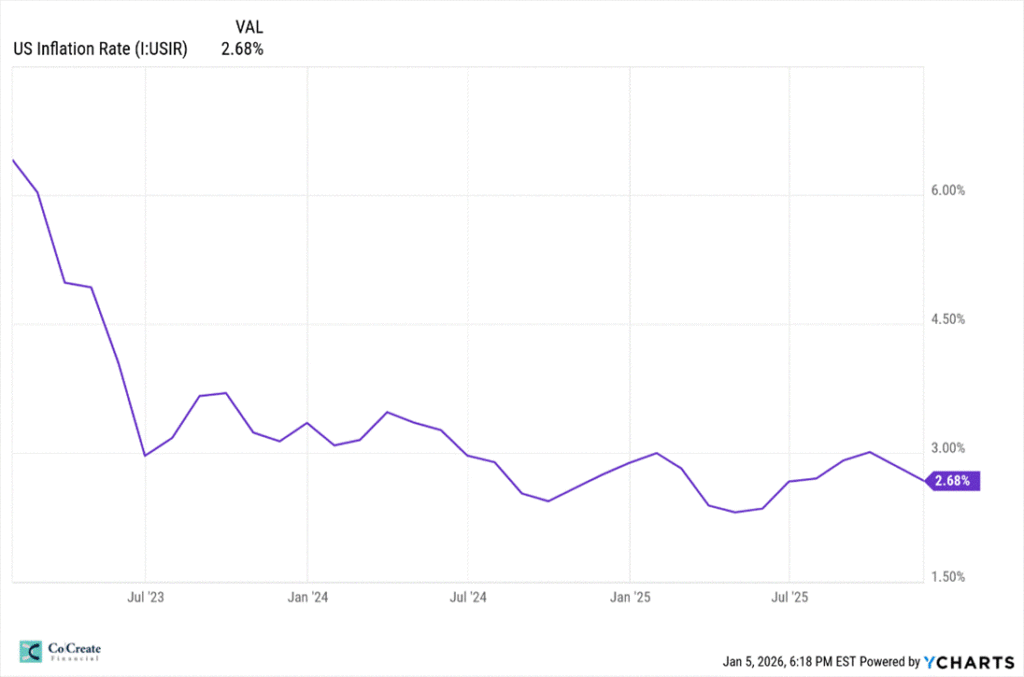
This graph depicts the U.S. inflation rate over the past three years. The broader trend still points towards gradual improvement, and we can navigate the uncertainty by remaining diversified, focusing on fundamentals, and avoiding emotional decisions based on fleeting headlines.
Throughout 2025, central banks, led by the Federal Reserve, took a cautious approach to interest rate decisions. After raising interest rates aggressively in prior years to fight inflation, policymakers shifted towards a slower, more thoughtful strategy.
Interest rates deal with the cost of borrowing money. When rates go up, loans become more expensive and spending tends to slow. When rates go down, loans become cheaper and spending increases. One of the Federal Reserve’s duties is to adjust rates to help keep inflation under control while also supporting economic growth.
Since inflation moved up and down during the year, expectations surrounding possible rate cuts were inconsistent. At times, investors expected rates to fall sooner, but when inflation readings came in higher, the Fed signaled it was willing to wait to make a move until they had a more complete picture.
Federal Reserve Chair Jerome Powell repeatedly emphasized that decisions would depend on clear progress in the data, not on what markets hoped would happen. The Fed needed tangible proof that inflation was improving.
On December 10, the Fed lowered interest rates by 25 basis points, which equals 0.25%. This was the third rate cut of the year. These small cuts suggest growing confidence that inflation is moving in the right direction, but again, these things take time and rate cuts do not bring change overnight.
Even as inflation started to cool, borrowing money remained expensive throughout much of 2025. Mortgage rates remained high, adding to the slower activity in the housing market and affecting affordability for buyers and refinancers. Higher monthly payments made homes less affordable, and fewer people chose to refinance their existing mortgages. This kept many buyers on the sidelines and reduced overall housing demand.
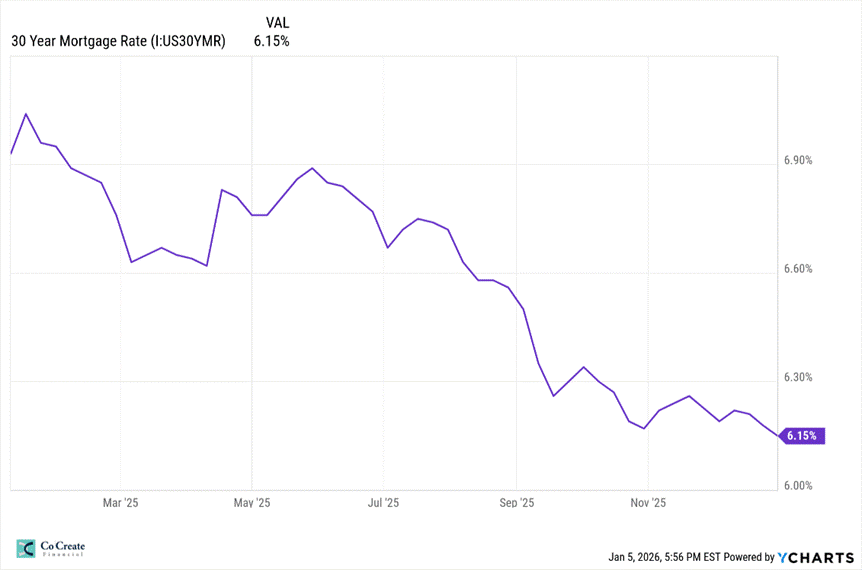
The chart above tracks the 30-year fixed mortgage rate, which is the most common home loan in the U.S. The line shows how mortgage rates moved throughout the year. When the line goes down, borrowing becomes slightly cheaper. When it stays high, monthly payments remain a challenge for buyers.
Although mortgage rates declined some towards the end of the year, they remained well above the low levels we’ve seen in other years, finishing around 6.15%. While this drop offered some relief, rates were still high enough to limit affordability for many households.
Higher interest rates also affected businesses. Companies faced higher financing costs, which made them more cautious about expanding, hiring, and investing in new projects. For consumers, borrowing became more expensive across credit cards, auto loans, and personal loans, making everyday purchases harder to finance and encouraging households to be more selective with spending.
Mortgage rates will take longer to come down, even if the Federal Reserve continues to cut interest rates. While rate cuts help lower short-term borrowing costs, mortgage rates are influenced by more than just Fed policy. Meaningful relief for homebuyers will require steady improvement in inflation and economic stability over time.
Interest rate movements had a broad impact on markets in 2025. Bond prices moved as rate expectations shifted. When interest rates stay high, existing bonds lose value, but new bonds offer higher yields, meaning better income potential going forward.
Stocks also experienced periods of volatility throughout the year. Higher interest rates make borrowing more expensive for companies and reduce the value of their future earnings, which can put pressure on stock prices. As investors adjusted to these conditions, markets reacted more sharply to economic data and rate expectations.
Despite short term swings, the higher-rate environment reinforced the importance of diversification. Balanced portfolios tended to perform more steadily, as income-generating assets played a larger role and helped offset equity volatility.
Economic growth in 2025 was more resilient than many early forecasts suggested. While higher interest rates were expected to significantly slow down activity, overall GDP growth remained positive, though more moderate than in prior years. GDP is a simple way to measure the health of the economy. It represents the total value of all goods and services produced in a country over a certain period. On the one hand, the U.S. economy continued to expand at a steady pace rather than experiencing any sharp contractions, showing its ability to adapt to tighter financial conditions. On the other hand, AI investment was responsible for approximately 92% of GDP growth in 2025 and tariffs appear to be costing about 1% of GDP.
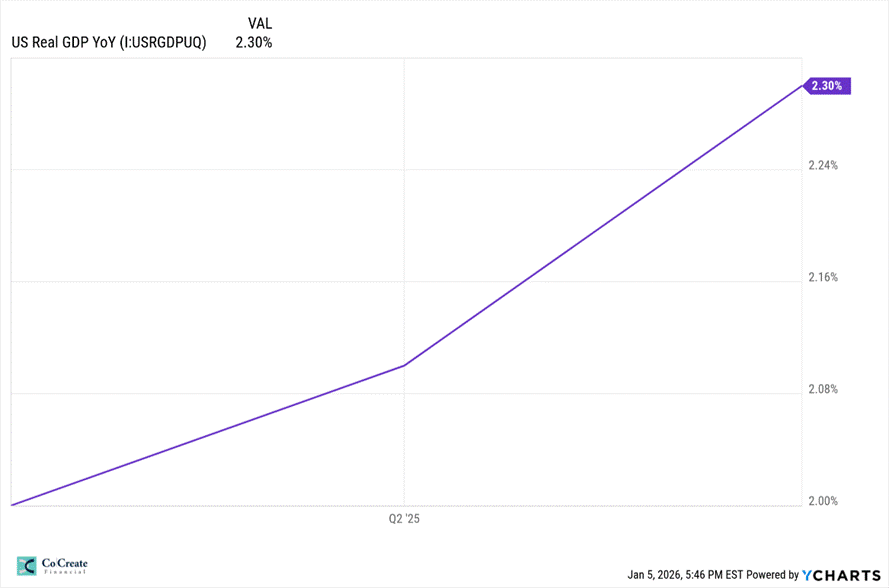
As we can see in the graph above, which measures U.S. GDP throughout 2025, the slower pace of growth suggests the economy is settling into a healthier balance. Instead of growing too fast or slowing down too much, businesses and consumers adjusted their spending and investment decisions at a more sustainable pace.
The job market remained relatively stable throughout the year, though hiring slowed compared to the rapid pace seen in recent years. According to the Bureau of Labor Statistics (BLS), total employment continued to grow, particularly in areas like health care and service-related jobs. The unemployment rate, which measures the number of people actively looking for work but unable to find it, edged slightly higher but remained near normal historical levels. This leads to a cooling job market rather than a major slowdown. As I’ve mentioned before, employers just became more selective with hiring as interest rates stayed high and economic growth softened. One notable change was a 9.2% decline in federal government employment, as hiring slowed and some government roles were reduced. This contributed to the overall deceleration of job growth.
Consumer spending in 2025 remained stronger than expected, despite the higher interest rates and prices that continued to impact people’s budgets. Solid employment and steady wage growth allowed many households to keep spending, especially on everyday needs, which helped support overall economic growth. However, when it came to discretionary purchases, consumers were much more cautious.
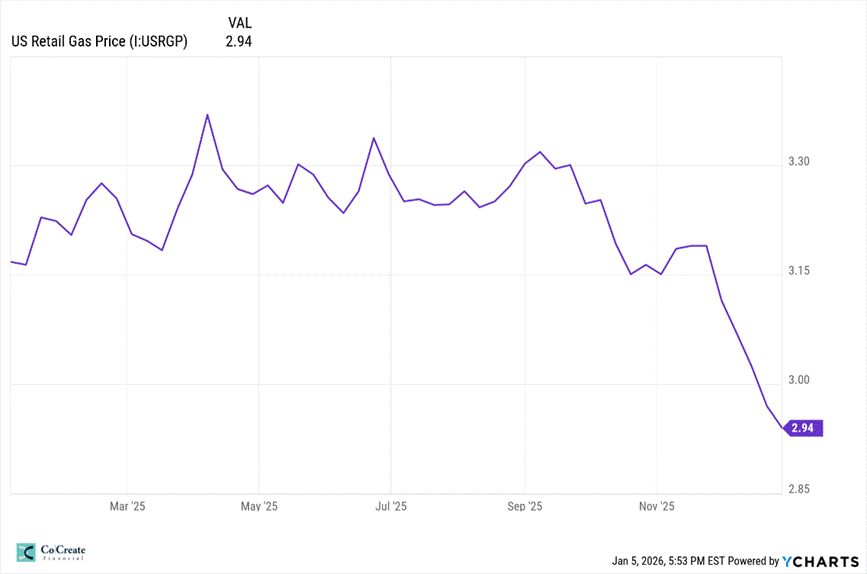
This U.S. Retail Gas Price graph highlights a positive for consumers, and a possible factor as to why people were able to keep spending. Gas prices fluctuated during the year but declined towards the end of 2025, finishing just under $3 per gallon. These lower gas prices could have helped free up budgets and allow for more spending elsewhere.
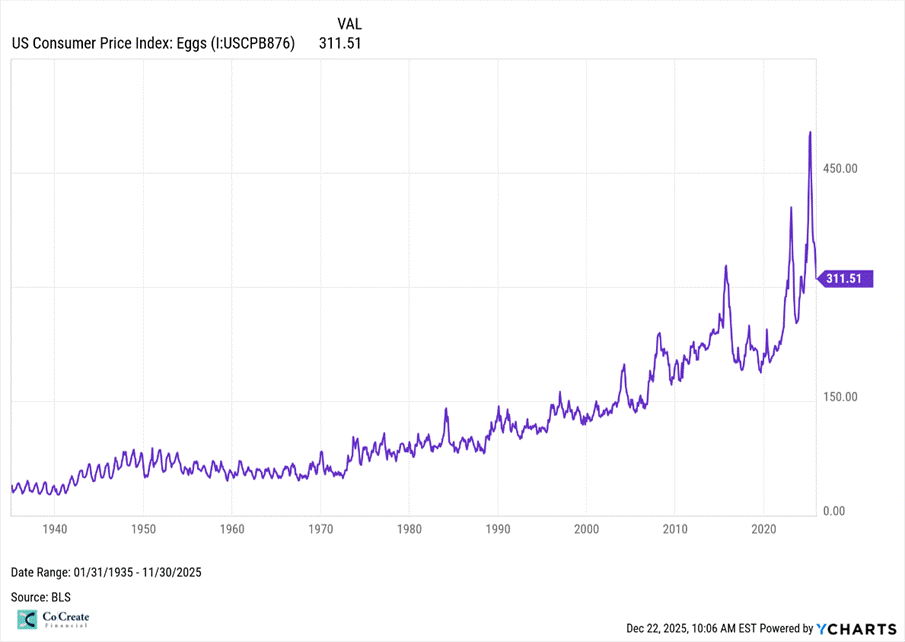
However, this long-term chart tracking egg prices tells a different story. While prices naturally rise over time due to inflation, the sharp increases in recent years stand out compared to historical trends. Eggs are a basic household staple, so rising prices here highlight how higher everyday costs have become more noticeable for consumers (if you’re spending $311 on eggs, you must be buying the Costco-size package).
Consumer spending in 2025 was less about excess and more about adaptation, which we’ve seen is a common theme in the overall market. Instead of cutting spending dramatically and abruptly, people adjusted how and where they spent their money. Lower fuel prices helped offset higher costs elsewhere but persistent increases in everyday items, like groceries, kept consumers cautious. From the start of the year, people felt a lot of hesitation as the economy sent mixed signals and pulled sentiment in different directions. Despite the concerns, the economy proved to be more resilient than many initially had expected.
2025 was a year of adjustment and adaptation. Market reactions were shaped by big policy shifts, political headlines, and changing expectations surrounding inflation and interest rates. While there were times of volatility, investors spent much of the year dealing with uncertainty and navigating the complex economic environment. Several key events and themes stood out and played a vital role in shaping market behavior.
In early April, on a day coined “Liberation Day”, the President announced broad tariffs on imported goods. The announcement triggered sharp and immediate market reactions, stocks fell quickly as investors tried to assess the potential impacts on inflation, global trade, and corporate profits.
As the year progressed, markets stabilized as people received more clarity about how the tariffs would be implemented and which industries would be most affected. While uncertainty remained during periods of negotiation, the initial shock faded as expectations adjusted.
Ongoing global trade tensions and the influx of new tariff policies added another layer of unpredictability. Rising trade barriers and high-profile negotiations influenced expectations for economic growth and international investment.
At times, discussions about scaling back harsher policies helped restore market sentiment, but renewed tensions would harm confidence once again. The shifting dynamics made long-term planning more difficult for businesses and investors.
Inflation continued to cool compared to prior years, but pricing pressures remained a central concern for investors, policymakers, and the everyday American. Even as progress was made, inflation did not drop quickly or smoothly.
Market reactions were often influenced more by headlines and policy signals than by long-term fundamentals, however this is not surprising nor rare. Short-term swings are natural, but the constant changes in policies emphasized the influence of these swings.
The rapid rise of artificial intelligence became a defining theme of 2025. Companies connected to AI saw massive increases in valuation as investors rushed to gain exposure to next “best” thing. Much of the AI investment came from the AI industry itself. We’ve discussed AI in previous articles and will be continuing to unpack the risks and opportunities.
But concerns about an “AI bubble” emerged, as people began to grow wary of the super high stock prices that did not seem to be in line with AI companies’ financial situation, leading to even more volatility within the industry. Moreover, there is an abundance of evidence that those implementing AI are NOT yet seeing a return on their investment.[1] We have been careful to limit our exposure to the risks of the AI industry throughout the year.
Fiscal policy remained a key theme in 2025, including changes to tax policy and ongoing debates over government spending.
New legislation extended and modified tax provisions for businesses and individuals, but the effects of “The One, Big, Beautiful Bill” were uneven across industries, with some sectors benefiting more than others.
The 43-day government shutdown that began in October 2025 and finally ended mid-November added to the ambiguity. While the shutdown was resolved, it brought even more short-term volatility and disrupted government services and personnel.
[1] https://mlq.ai/media/quarterly_decks/v0.1_State_of_AI_in_Business_2025_Report.pdf;
CFO Outlook for 2026: Tariffs, Hiring, Prices, and AI Impact | Richmond Fed
Gift stacking, also known as gift bunching, is a great strategy to maximize charitable impact while also boosting your tax efficiency.
This strategy allows you to combine multiple years of charitable giving into one tax year, and you can increase your itemized deduction amount above the standard deduction threshold, allowing you to take advantage of more meaningful tax savings than if you would have spread those same gifts out annually.
This can be done by simply making a large gift to a charity of your choice in a given year and foregoing gifts the next, or by putting that money into a Donor Advised Fund (DAF) to fund multiple years of giving. When you pre-fund your charitable donations into a DAF, you immediately receive the full tax deduction in the year you contribute, even if the funds are not distributed to the charities until future years.
This gives you flexibility in how and when the money is given, while still locking in the tax benefit today, making gift stacking an efficient planning technique for higher-income years, or for alternating between itemizing and taking the standard deduction.
If you don’t use gift stacking and instead spread your charitable giving evenly each year, you may not receive a substantial tax benefit, or any tax benefit at all, if your annual donations do not exceed the standard deduction amount. Many people mistakenly believe that if they donate annually, they automatically receive a higher deduction, but this is not always the case.
Without gift stacking, your charitable gifts could be absorbed into the standard deduction amount, meaning that you’d lose out on potential additional tax savings that could’ve been unlocked with more strategic timing.
Combining gift stacking with a Donor Advised Fund is a powerful strategy that allows you to maximize your deductions by alternating between itemizing and taking the standard deduction while still allowing you to make consistent gifts to charity each year.
2025.08.27 Podcast Episode 1
Christa: Welcome everyone. We're excited for you to join us for our very first podcast for Co-Create Financial. I'm Christa.
Matt: I'm Matt,
Christa: and we're excited to talk to you about a couple of things. First, we're gonna cover just some general things that we see in the market right now, how we're approaching our client portfolios, and then we'll also talk about some firm updates and general things we have going on here at Co-Create Financial.
Matt: Awesome. I wanted to jump in here, and talk about a couple of things before the AI section where we're looking at some more, more broad issues that, you might see in the headlines, you might see in the news. And then we'll dive into the kind of the big topic that's the interesting one certainly one for us, as investors and just as human beings.
Christa: It's a question on everybody's mind lately, what's going on with AI? How are you implementing it? What does it look like and what's it changing?
Matt: I mean, one of the most fun things you can do is get on YouTube and watch videos of people trying to stump AI. Uh, it's, it's pretty phenomenal. If you do that, it's a good laugh.
With that, the first thing that I want to talk about is inflation. And the concept of rate cuts, because this is kind of the, this is the most common thing that you're hearing about in terms of risks. So when we look at it I wanna be clear, the Federal Reserve doesn't really control the economy.
They can kind of manipulate, some pricing and some capital flows, over the short term, but they really don't control the economy. That's businesses and profits and things like that. And if a business can borrow more effectively, then they're gonna have a better profit margin maybe for a little while, or they might invest and spend some more money to get some things flowing.
But overall, interest rates don't actually control the economy or market growth over time. They just kind of put some guardrails on it and a little bit of pressure. When we look at inflation though, inflation is really caused by an increase in the amount of money that exists in the economy.
It's the number of dollars for computers or for iPads or mugs or whatever it might be, t-shirts or dress shirts, whatever it is that, that you're buying. If there are more dollars the person selling that good can charge more for it because there's just more available. So we look at that and five years ago when we went into COVID, and we've talked about this a lot, feel free to explore some of our other content that, we've put out because we've talked about this ad nauseum since COVID hit.
But when you increase the amount of money the way that we did, that's in circulation, which has never been done, nothing's ever come close. That just simply increases inflation and you can buy less with each dollar when you do that. But what we've been kind of been saying over time is that as you have this increase in money supply, the price of goods and services has to increase until they're about it at equilibrium.
And that's kind of where we are right now. There are some other factors that are continuing to drive inflation forward a little bit but overall we're at a place where that issue's really resolved itself to some extent.
Christa: Yeah it's important to realize that during the COVID shutdown, there was just huge amounts of money that were injected into the economy, and that's really what drove these inflation issues is just needing to normalize that because inflation really is a monetary phenomenon.
And just like Matt said about how many dollars are chasing the goods and services available.
Matt: That's, that's exactly right. With all of that, the other thing we see with those, the inflation is the tariff issue, which is continuing to unfold. it is questionable how much the broad-based tariffs can be implemented, um, just based on, court rulings and the way the law is written.
Certainly with China and the trade war there, there's some issues where there is the authority to impose certain tariffs in some of those. And those do increase inflation because all that gets passed on to the end consumer to some extent or another, at least in the short term while all of that plays out.
So, we're getting a lot of information about all of these things in real time, and that's a lot of really mixed information. Some of that's delayed. So there are these issues about what's really going on in the economy is there transparency, with everything that we're learning.
And it's pretty good overall.
The information is pretty clear. Most of it's available with the government shutdown, which we'll talk about in just a moment. that really is delaying some information, but there are some side avenues to getting some clarity about what's going on.
There's always a little bit of a lack of transparency and a lack of accuracy in, economic numbers until they're really studied and revised six months a year down the line with more real data. Some of that information is saying that the economy's continuing to accelerate. We do have GDP growth right now, things like that, but we also see some other issues where it says the economy's decelerating jobs are frozen, businesses aren't spending money.
We have a actually a lot more earnings misses and, in the stock market where companies aren't hitting what their profit expectations were. Mm-hmm. then we have in recent quarter. So we're seeing more and more, issues with all of those things and leads to this question of are we headed into a recession?
Mm-hmm. And we've talked about that a number of times with many of our clients. We've talked, we've kind of written some about that too. Our expectations for recession are that really that we're gonna continue in the recession that we've kind of quietly been in. I like to call it a ghost recession.
Mm-hmm. Looking at that ghost recession, you know, we've seen people struggling because the grocery budgets are increasing. We see people struggling to hire employees, because of the cost of wages and it's freezing up the labor market. We see all those things playing out, and that's really when a recession starts, is when spending starts to get tighter for people.
And so when we look at that question, we've been in it, is it gonna get worse? Is it gonna get better? That's a different question. I think that there are some reasons to be hopeful about the economy, but I also think that there are a lot of risks.
Christa: You know, one of the things that's, important to remember is that for so many of us, we think of recession as, you know, the great financial crisis of '08, and we kind of anchor to that side of it.
But the reality is most recessions are not that extreme. And so even if we're talking about being in a recessionary environment, it doesn't mean the bottom's falling out of everything like it did in '08. And I think we've seen a lot of signs of people just tightening up. And then we've also seen some divergence between higher income earners and kind of people a little bit lower end on the spectrum where there's a lot of difference in how things are hitting people.
But like Matt said, everybody feels the grocery bill and is starting to make some adjustments in their spending. There's certain things that they won't give up, but other things that they're making adjustments on, that are maybe a little bit more mild. So it's been an interesting phenomenon to watch.
Matt: Yeah. And, and I believe if, we're looking at kind of the different income, levels within, society, the top 20, was it top 25% of people that are, continuing to spend as they have been. But when we look at the bottom 75% of the income brackets, they're really compressing. They're spending, they're tight, they're feeling this.
So there are a lot of things that are kind of challenging in that front for the majority of people in our communities. Mm-hmm.
On that note, I do wanna mention with the government shutdowns. We've had a lot of government shutdowns. I don't know if you recall the number that we, that we've had.
It's escaping my mind at the moment, but we have the government shutdowns all shuts down all the time. Unfortunately it's becoming more and more common as we get more polarized and have more gridlock in Washington. But, we've never had a recession, follow a government shutdown really in close proximity at all.
So, that when we look at those government shutdowns, they don't lead to recessions. They don't lead to significant economic problems. So while we're concerned about our government's ability to get things done and our government's ability to work together, I don't think that this government shutdown is gonna drive us into a recession or an economic crisis or a catastrophe.
Certainly it affects individual lives, people working for the government, but it's not gonna cause, a significant economic issue in part because a capitalist system doesn't function on government spending. It functions on corporate profits and private business. I'm going out and making money, paying employees, people buying and selling goods.
It's not about the government telling it what to do.
Christa: Mm-hmm.
Matt: So I think that sounds really good.
Christa: Exactly. Yeah. We. You know, it's certainly concerning the government being shut down on some levels and especially as it impacts individuals, but it's not shutting down our economy and that's an important thing to remember.
So let's dive into this question on AI and what that means for investments and what we're seeing now in the current market because there has been this explosion within the stock market and anything that has anything to do with AI. So do you wanna chat some about that, Matt, and talk about how we're viewing and engaging that.
Matt: Yeah, absolutely. The AI industry, let's call 'em the hyperscalers but really this artificial and intelligence industry has driven a tremendous amount of growth, not just in these companies, but in the markets as a whole. When you look at some of these companies, you've got people that have got, 3, 4, 5, 900% returns on a singular stock. And the thing that really, it looks like the most is the .com bubble in the 1990s. When we think about that, everybody buying these, these stocks thinking, you know, this is gonna be the future. This technology's gonna change the world. and of course the internet did.
Mm-hmm. Um, but what's gonna be pets.com? And go out of business, what things are gonna survive? Even those, the companies that do survive take, I think Cisco for example, it was massive in the 1990s. Shot up in price, before the 2000 crash. And, of course, it came crashing down and Cisco's still around and it's still a great company.
But when you look at these tech companies, these NVIDIAs, these, Broadcom saw open AI, all these different tech companies that everybody's investing in, thinking this is gonna be the future. They've really shot up in a way that resembles that tech bubble. Mm-hmm. One of the things that we're hearing a lot is that, you know, this is different this time.
Christa: Yeah. A lot of people are saying that, they're saying, you know, AI is the future and things are moving so fast, and technology is being adopted so fast, so it's different. Right.
Matt: And because we're selling a service instead of just hopefully like having something turn out because of all the marketing hype.
There's a little bit of, there's some structural differences, going on, and we could get into how all the IPOs were going on in the nineties and if you really wanna talk about that, gimme a call. And I'm a little bit of a nerd, so I'd be happy to chat with you, but nobody wants to hear about that on a podcast.
Well, maybe some do, but not here.
Matt: So when we look at that, we have to, to really understand what's going on, and then how those are affecting, the overall market. So I'm gonna pull up a little illustration here, it's just a little chart on my whiteboard of the S&P500, which the S&P500 is a grouping of the 503.
My computer's not plugged in when you plug that in so you guys can see what we're talking about here. It's episode one. So when we're looking at the S&P500 it's the 503 largest companies that are traded on a US stock exchange. So these are all businesses that you can own.
And if, we're looking at this on my screen here, you can see the top companies of these. You've got Nvidia, Microsoft, Apple, Amazon, Broadcom, Meta, Alphabet and so going down, of course there are two different shares of Google, so Google shows up twice. But when we look at this, these are all grouped and ordered by size
so the S&P500 owns the most of the biggest companies.
Christa: That's why we refer to it as a cap weighted index. The companies at the top are a higher percentage of the index.
Matt: Yep. And so what is it about 40% if we were to look at, the top 10 or so companies here? I think that's gonna go down to about JP Morgan on my screen.
If somebody, you can count, you can see the whole, list of the top, 25 or so here on this screen. But this is about what, 40% of the S&P500, that's a massive amount of anybody that's in an index fund. That's a massive amount of what you own. It's a massive amount of market growth. The S&P500 is what people talk about when they say the stock market.
It's predominantly, they're talking about this right here, this grouping of 503 companies. And it's mostly these giant AI tech companies or tech companies that have AI exposure. If we go through it, apple doesn't, Amazon has some, but less than some of the others. Obviously Nvidia, Broadcom, Alphabet, all do, Tesla, doesn't have a ton, but, there's exposure, just with Grok AI and things like that through kind of by proxy with X. But Google, of course, so we're looking at these companies are really heavily influenced by AI and if you own an index fund, that's 40% of your portfolio. Yeah. This isn't how we invest, by the way. So when we're talking about this, we're talking about, a different strategy than what we're engaged in with our client portfolios.
Christa: Yeah, just emphasize that Nvidia alone is 7.5% of the S&P500. So, you might think you're diversified 'cause you're investing in 500 companies, but the top 10%, top 10 companies are 40%, which means that the remaining 60% is among those 490 companies. So, it's really quite focused on this AI space and the top companies.
Matt: So looking at those top companies then, when we're looking at this AI, well, I'm just gonna call it an AI bubble. I mean, Mark Zuckerberg's talked about a possibility there being an AI bubble. So is the CEO of Open AI. So like, I think it's fair to call this, to kind of call this what it is.
There's this bubble that's built around, the future of AI, it's around what need it might produce in the future, and to give you an idea of the size of this bubble, when we look at it right now, artificial intelligence is, producing about 50, 50 billion in revenue, that sector of the industry, and these are companies that people are paying
$125 or 125% of earnings. So $125 for every dollar of earnings. That's a lot of money. It's expensive. To give you an idea, it would take somewhere between 2 and $5 trillion of revenue coming in from these companies in order to cover that.
Christa: Justify the cost of the multiples that people are playing at
and just to back things up a little bit, when we look at stock prices and stock valuations, we say, you know, a company for it to be worth investing in and owning means that it has to pay you as an owner. It has to be producing profit. And that's what we're buying. We're buying an income stream for the company.
And sometimes there's, you know, a lot of people invest in kind of the speculative side of investing, which is saying, Hey, maybe this company doesn't make money now. Or maybe they don't make a lot of money now, but we think they will in the future. And that's what people are doing on the AI side. But the thing is, is that we have to eventually get to the point where it produces enough revenue to justify those costs, because otherwise it's just eating up all that money and that's gonna come crashing down at some point. And so that's the fundamentals of how we view investing in the stock market, is what is the cash flow and what's that gonna pay you as an owner and how are you gonna get a return on your investment?
And it's not just hopefully it goes up more. There has to be a reason it's gonna go up more and that's cash flow.
Matt: Yep. So there's this massive expansion in revenue that AI needs. We're seeing some other challenges within the AI world, let's call it. MIT just released a study, recently that reported that 95% of AI startup, or implementations pilot programs is the term,
that 95% of those fail to deliver or return on investment. So all of this adoption of artificial intelligence and companies saying we're gonna make things efficient, streamlined, we're gonna generate profit, reduce the number of jobs that we need to have, which is an entirely different side of this conversation.
But they're looking at all this information. They're saying, we're gonna make this work for us, and it's not happening. And so this revenue growth, 50 billion to five, two to 5 trillion. We're struggling to have the productivity on the front end, on the user end in order to drive that growth. That's not that it won't be there, just like the internet changed the world.
Artificial intelligence can change the world, but we have to have that start, have it start to be functional and useful. The MIT study also looked into what it was gonna do to jobs since I brought it up and it's probably not going to end up eliminating very many jobs, at least not for the foreseeable future according to that perspective.
We're also right about at peak data. Which that means that we've used all the data that it needs to train on. There's not a lot more out there and so we have this impending crisis of running out of information for AI to learn. And if you watch some of the YouTube videos about people [00:18:00] stumping AI, how many Rs are in strawberry or is 9.11 bigger than 9.9?
Things that seem like easy questions that AI can't pull together. We're running out of data for it to learn from, and it's starting to supplement that with AI produced content, which is unreliable yet. And so there's this a big issue that's kind of coming down the pike with that component of it.
Christa: So Matt, so we've kind of covered that. You know, we certainly have concerns about investing in the AI space. We recognize that it will have profound implications for the future, but we're not seeing a clear path to justifying the current prices for these companies. And we do expect the valuations on those at some point.
We don't know when. We can't know when we'll come back down to earth. How are we approaching this from within our investment philosophy and what we're doing for our clients and how are we mitigating these risks and what can people kind of look to and see in their portfolios?
Matt: Yeah, absolutely. So first thing we're doing is we're looking for the appropriate exit points. We don't have a lot of exposure to artificial intelligence directly these hyperscalers. We do have some that was coincidental because we bought them as best in class businesses before this AI trend took off.
And so some of that we've been able to ride along and we've been able to take some profits out as we go. That's a really important thing is you're making money in the stock market, is to know when to take profits. out so that you're not overexposed. But with that, we're, we're looking for, you know, what are the exit points for these companies where you have a 500% return on whatever AI stock, when do you get out and what's gonna change it?
In the 1990 to two, uh, late nineties led to the 2000 bubble coming down and really it was kind of this turning point where it was, you know, feds changed some interest rates and started kind of unraveling and it was just, there was this tipping point and we don't know what that's gonna be. So we're looking to de-risk in our portfolios from the AI exposure so that we're not dependent on this massive increase of AI data.
I have a chart on my screen here that we can share AI the orange line here is the S&P500, and the purple line is the S&P500 as well. But remember how we talked about that, the top companies being the biggest ones, and they're about 40%. Well, the purple line is if you just took them at an equal part of the S&P500, instead of having it weighted like that.
And functionally, what this does is this gives us a really good idea of the difference in pricing between AI and the rest of American businesses.
Christa: We've really seen, you know, it seems like so many things have gone up together in this AI level, but when you get into the data, if there's really been a clear divergence between companies in this tech AI space and companies that are just doing other business and good business.
And so that's one of the things that we're watching is that divergence in the space.
Matt: Yep. So our portfolios and the investments that we hold much more closely reflect the S&P500 equal weight index than they do the S&P500, in part because we have investments that are balanced appropriately and diversified in an appropriate mix versus being concentrated and AI or any other given or necessary specific industry.
The other thing that we're looking at is, just having consistent and steady cash flow coming in, and not relying on future promises of revenue that aren't gonna come. I mean that all these AI companies are relying on, you know. Hundred, $500 billion investments from one another. And they're dependent on all of these.
And it's kind of the circular mix of capital that they need in order to survive. And products that they wanna buy from other companies that are needing their own investment. And this big kind of circular problem. In fact, I think I have a quote somewhere in our notes about that. I don't know
If that's in here, but it's pretty great. This was from a JP Morgan, research analyst. It says, Oracle stock jumps by 25% after being promised $60 billion a year from Open AI. An amount of money that open AI doesn't earn yet to provide cloud computing facilities that Oracle hasn't built yet.
And which require 4.5 gigawatts of power, the equivalent of 2.25 Hoover dams or four nuclear power plants, as well as increased borrowing by Oracle whose debt to equity ratios already 500% compared to 50% for Amazon or 30% for Microsoft, and even less at Meta and Google. In other words, the tech capital cycle may be about to change.
Christa: So we've seen a lot of excitement around how these companies are investing in each other. But none of it's come to fruition yet, and we're very concerned about that.
Matt: Yep. So what we do in our portfolios then is we own these dividend yielding companies. Predominantly we're looking at companies that have free cash flow.
We're looking at companies that have a profit margin, that have a product that people are buying. That is something that's different than the AI industry in this AI cycle, and it doesn't look as exciting. It's not as fun to, to kind of do the slow and steady, especially when things are taking off in a bubble like this.
But we're really trying to go to the tried and true the things that are gonna give you a good long-term return, a rising stream of income from dividends where that's safe and secure. I mean, there, there are always risks that exists in the market and in business ownership. So something could happen to one of these, but we diversify our portfolios and measure that
so that we're making sure that we're not too exposed to anything in particular that's gonna cause our clients to have a lapse in cash flow or any kind of long-term issue with growth kind of going forward. So we're expecting that to be a much more responsible, tried and true way to get a good return over
the long haul and asking when do we get out of the things that have this excess risk.
Christa: Yeah. Absolutely. So, kind of to recap there, it's just important to remember as you hear the bad talk around AI there are concerns there. There are major risks, and we are actively mitigating those in our client portfolios and making sure that our clients are set up for success on the long haul with tried and true research backed methods, not chasing the next hot stock.
So you don't have to be afraid that you have this exposure that the S&P500 does. We've already mitigated that and are constantly working on that in our portfolios.
Matt: Yeah, we do believe that there's growth opportunity out there and that there's a way to, make money in our stock markets and our other financial capital markets.
So this isn't a, we should pull the rip cord and get out. We need to be very strategic and very careful about how we measure risk and reward in our portfolios as we manage those on a company by company basis. And we do that and measure that every month by the way, we get together and sit down as a team and review every holding that we have and make sure that,
all of the financials look good and that everything is squared away and we're confident in its ability to continue to perform like we need it to for our clients.
Before we talk about the last topic that I think is a really significant concern right now in our economy, in our markets, I just kind of wanted to talk about a couple of the things that we have going on around our firm.
We've been doing a lot of work. Yeah. Over the last year.
Christa: Yeah. We've been doing a lot of building out infrastructure within our firm and some exciting things that are coming up.
Matt: Yeah, our goal is always to make a really great experience for you as the end client and being a small business, we have the ability to adapt and do a lot of fun things.
The first thing that,I wanna talk about is kind of my passion project, and maybe you can talk about, the addition of Altruist just a little bit after that. We have added the ability to vote client proxies. Which I'll tell you what that means. Okay. Because there's gonna be a new agreement that we're gonna start working into our client conversations and talking about with individually as we sit down with each of you.
But investments can change the world. The stock market is actually a democracy. Everybody likes to complain about corporate America and what it's doing in our world, but we actually have the ability as business owners of these companies to have a voice and you get a vote and there are all kinds of things that show up on these ballots that come from the owners of a stock that are really significant.
A recent one that comes to mind was related to Facebook and children getting access to pornography. Some of these might be about environmental stewardship. Some of these might be about a lot of other different topics that people are passionate about and that you think are important.
What people don't realize is that most of the time you're giving your vote, especially if you own a fund and you don't work with us, where we own the investments directly, you're giving your vote to somebody else and most of the time you're probably not gonna agree with them.
Christa: Yeah. So if you own a mutual fund or an ETF, if you're in those vehicles, that fund manager gets to vote your shares.
Matt: Yeah. So to talk about this Facebook example, about 95% of the votes that went in aligned with management and said that we're not gonna do any investigating or work on this issue that pertains to children receiving access to pornography. And it was somebody who owned Meta stock that brought that to their attention.
And you don't have to even own a lot to do that. Well, one of the things that we've done is we've gotten set up so that we can actually engage with you so that you can authorize us to go through those ballots that you receive in the mail and say, this looks like junk mail. And you check it. Those are actually really important to you.
If you want to, we can vote that for you and help give voice to things that really matter. Things that are important that can direct, kind of the future of our society and help set culture here, right here in our country and our community. o we're really, really excited about that.
Christa: Yeah. So we'll be talking more with our clients about how we started that process and roll that out over time here.
The other update we wanna share with you is currently we've been in this situation where we custody all our client accounts at Charles Schwab and we are going to continue to contract with Charles Schwab and custody client accounts at Charles Schwab.
However, we have also onboarded an additional custodian to enhance our client experience. Many of our clients have a great experience at Charles Schwab, but some of them, it can be a little clunky. And so we have onboarded with a firm called Altruist that offers a more tech forward streamlined experience that I think for some of our clients is going to be a better fit and a better experience than what they're currently receiving on Charles Schwab.
There are some nuances as to what types of accounts are a better fit for one or the other. So this is not a blanket sweep. If you're happy with Charles Schwab, we're happy to keep you there, but if for some reason there's some challenges with just how you're feeling about the paperwork processes or updates to your accounts, it might be a good time for us to transition you to our other custodian Altruist because we're excited about what that'll mean for the future.
Or junk
Matt: mail or junk mail,
Christa: less junk
Matt: mail,
Christa: and it'll just be a more streamlined experience for our clients.
Matt: Yeah, we're really excited about that. It's just gonna help us optimize even more. And of course, if you're on one or the other, it's always gonna be available through your co-create login or on our app.
So you can access all of your information and data there at any time.
So the last thing on the agenda is to talk about the final piece. And I think this is one of the bigger risks over the long term to our economy. Kind of even more than the AI bubble that's gonna come back down to Earth and probably skyrocket again and come back down to earth in this up and down cycle.
But I think one of the biggest risks that we actually see, right now that I just wanna bring attention to is what I would call the degradation of the free markets. We're seeing a lot of government influence, and this is not just this current administration, it's also the previous one and the one before that this has been going on for a while.
And so when the government gets involved in business it slows growth, it creates bureaucracy. That's not to say that we don't need any regulation, or any government involvement whatsoever, but it's saying we need to balance that very carefully and very appropriately. And one of the things that we're seeing is, a shift in how the government and gets engaged with business and owning golden shares of, say, Intel or negotiating for ownership stakes in these businesses.
The Communist Party in China actually owns golden shares in every business that's Chinese. So when we talk about owning golden shares or government owning business, we're actually socializing a lot of the free market economy that we have. Whether that's good or bad. We will find out someday.
We don't know, but it is a fundamental shift in the way that our capital markets work and the way that our government systems and our investing strategies can integrate it. And so it's something that we're gonna be paying attention to over the next decade. I'm very carefully is how the government's inter engaging in the capital markets
because it has a significant impact on the long-term performance. I mean, for better or worse.
Christa: Thank you for joining us for our very first podcast. We appreciate all of you and please feel free to reach out with any questions if anything you wanna chat about more and we look forward to sharing with you again soon.
One of the most tax-efficient ways to give is by donating appreciated assets, like stock or real estate. When you donate assets that have increased in value since you purchased them, you avoid paying capital gains tax on the appreciation.
If you itemize deductions, you can also claim the asset’s full fair market value as a charitable contribution (subject to limitations). This makes donating appreciated assets significantly more efficient than giving cash, almost like receiving a double benefit since there is no capital gains tax and you can take a full-value deduction.
Here’s an example:
Imagine you purchased stock for $5,000, and over time it grows to $50,000. You plan to donate $50,000 to a charity you care about, so instead of giving cash, you donate the shares. You receive a deduction for the full $50,000 gift, and you avoid paying capital gains tax on the $45,000 appreciation. The charity can sell the shares tax-free, allowing your full gift to support their mission.
Donating highly appreciated assets allows you to maximize your impact by being tax efficient. It can also be a smart strategy for investors who want to rebalance a diversified portfolio while supporting meaningful causes. By funneling your giving money into your investment account and giving appreciated shares instead, you are able to limit your capital gains and replace low-cost basis stocks to reduce your future taxes.
Common assets you can donate include:
How to donate appreciated assets:
To donate publicly traded stock, your financial adviser can help you initiate a transfer directly to the charity or to a Donor Advised Fund. You will need to contact the charity to ensure they accept stock donations and acquire the charity’s investment account number and their DTC number. It’s important to notify the organization ahead of time so they know to expect your gift and can issue the appropriate receipt. For non-traditional assets, like real estate, business interests, or crypto, reach out to the charity first to confirm they can accept the gift and complete any required steps. Often a Donor Advised Fund (DAF) can help to facilitate this type of gift when a charity is unable to do so. Donating business or real estate gifts require additional planning well in advance of your transaction. It is a good idea to connect with our team as well as your CPA and attorney(s) when you begin considering this type of gift.
Qualified Charitable Distributions (QCDs) are an excellent tool for retirees to maximize the tax benefits of giving. A QCD is a tax-efficient way for individuals age 70 ½ or older to give directly from their Individual Retirement Account (IRA) to a qualified charity. Rather than withdrawing funds from an IRA, paying income taxes on the distribution, and then donating the after-tax amount, a QCD allows the gift to go directly from the IRA to the charity of your choice, keeping the distribution excluded from reportable income.
To qualify, you must be at least 70 ½ years old at the time of the distribution, and the gift must come from a traditional IRA. Each individual can contribute up to $100,000 per year ($200,000 for married couples filing jointly), and gifts must be made directly to a qualified 501(c)(3) public charity. It’s important to note that donor-advised funds, private foundations, and supporting organizations do not qualify for QCDs.
A great advantage of a QCD is that it can satisfy all or part of your Required Minimum Distribution (RMD) once you reach the age of 73. Since QCDs are excluded from taxable income, they lower your adjusted gross income (AGI), which could lower Social Security benefits taxes and help avoid higher Medicare premiums (called your “IRMA”). If you don’t itemize deductions, giving through a QCD is particularly beneficial because the gift never hits your income and no deduction is necessary.
For example, if your RMD for the year is $30,000 and you choose to make a $10,000 QCD, that $10,000 goes directly to your chosen charity and is excluded from taxable income. You would only then report the remaining $20,000 as income for the year.
By giving directly from an IRA, you can meet your RMD obligations, support charities of your choice, and reduce your tax liability.
Donor-Advised Funds (DAFs) offer a flexible and strategic way to support the causes you care about over the long term.
What is a Donor-Advised fund?
A DAF is a charitable giving account that allows you to contribute assets, receive an immediate tax deduction, and distribute funds to charities over time. This structure can be especially helpful if you want to plan your giving intentionally.
Here are a few key advantages of using a Donor-Advised Fund:
DAFs can typically accept complex gifts, such as shares of a closely held business, appreciated securities, or other non-cash assets. If the charity cannot receive a gift directly, you can donate the asset to your DAF instead. The fund can liquidate the assets and distribute the proceeds to the charity (or multiple charities) of your choice.
Money inside a DAF can be invested before it’s donated, and it will grow tax-free. Many sponsors offer impact-focused investment options. These investments can potentially grow your charitable pool, allowing you to give more over time. If the investments lose value, the loss occurs on funds you’ve already committed to charity.
If you are looking for a structured, tax-efficient, and scalable way to support the causes that mean the most to you, donor-advised funds may be an excellent option.
Other advantages:
